Category: Blog

Your blog category

  • Builder’s Risk vs. Construction Insurance: Which One Protects Your Project?

    Builder’s Risk vs. Construction Insurance: Which One Protects Your Project?

    A construction project brings together significant investments, multiple contractors, valuable materials, and constantly changing risks. The right insurance can help protect your project from unexpected setbacks, but choosing the right coverage starts with understanding what each policy is designed to do.

    Builder’s risk insurance protects the physical project while it is being built or renovated. Construction insurance is a broader term that may describe the complete insurance program supporting the project, including builder’s risk, liability, equipment, professional liability, and other specialized coverages.

    The two are not always alternatives. In many cases, builder’s risk is one important part of a broader construction insurance program.

    Understand the Difference. Protect What Matters.

    CoverageMain purposeCommonly protects
    Builder’s riskCovers physical loss or damage during constructionThe building, materials, temporary structures, and sometimes soft costs
    Construction insurance programAddresses the project’s broader risksProperty, liability, equipment, professional services, pollution, and delays

    The exact coverage depends on the policy wording, project details, insurer, and contractual requirements. A tailored review is important before construction begins, not after a loss occurs.

    What Is Builder’s Risk Insurance?

    Builder’s risk insurance, also called course of construction insurance, is a temporary property policy for a building project.

    It is designed to protect the work in progress and may cover:

    • The building or structure under construction
    • Building materials and supplies at the job site
    • Materials in transit or temporarily stored elsewhere, when included
    • Scaffolding, hoarding, and other temporary works
    • Certain construction equipment or temporary structures
    • Fire, theft, vandalism, wind, and other insured perils
    • Soft costs, such as additional professional fees or permit expenses, when added
    • Delay-related expenses or delay in start-up coverage, when available and appropriate

    Builder’s risk may apply to a new build, major renovation, commercial development, multi-unit property, or other qualifying construction project.

    Coverage normally begins when construction starts and ends when the project is completed, occupied, or otherwise reaches the policy’s defined completion point. The transition to permanent property insurance should be planned in advance.

    See What Builder’s Risk Does Not Cover

    Builder’s risk is not designed to cover every construction-related problem. Common exclusions or limitations may include:

    • Faulty workmanship itself
    • Design errors or professional negligence
    • General third-party liability
    • Worker injuries
    • Mechanical or electrical breakdown
    • Pre-existing damage
    • Certain types of water damage, vacancy, or weather-related losses
    • Construction delays that are not caused by an insured loss

    An insurer may cover resulting damage from an insured event even when the cost of correcting faulty workmanship is excluded. However, this depends on the policy wording and circumstances of the loss.

    That is why a detailed coverage review is essential for your project.

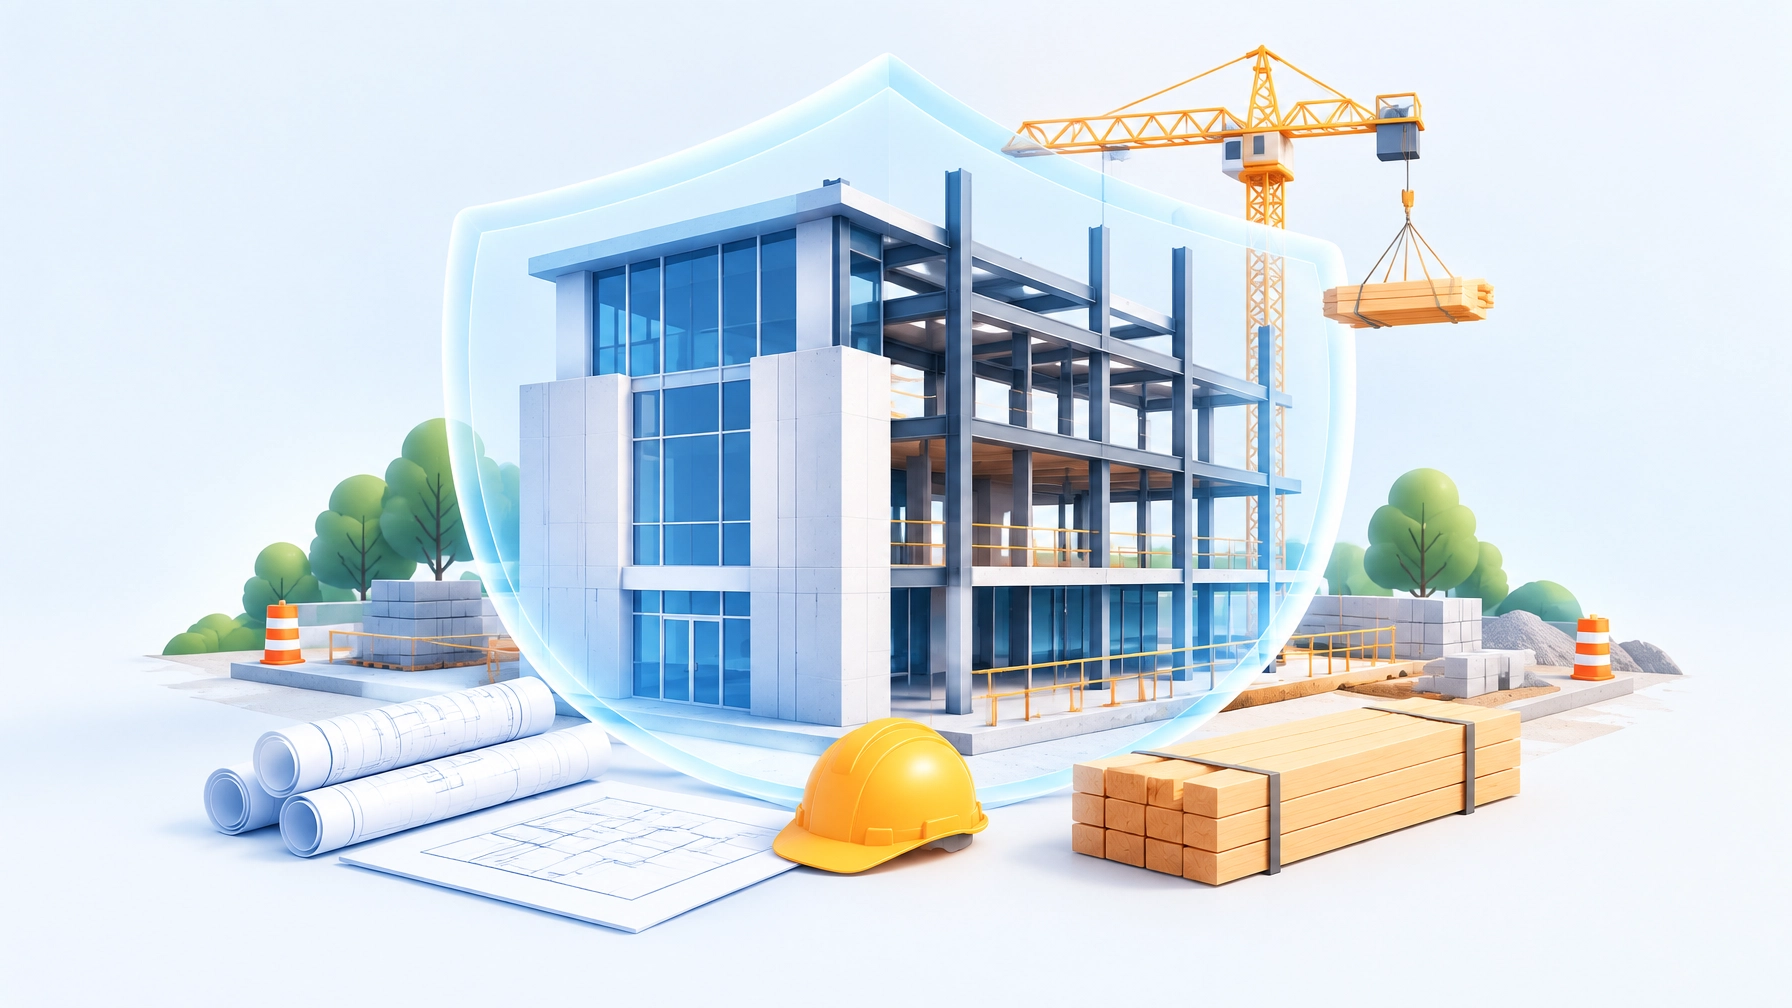
    Construction site and building materials protected by builder's risk coverage

    What Does Construction Insurance Include?

    “Construction insurance” is commonly used as an umbrella term. It can refer to the complete set of policies needed to protect a construction company, project owner, developer, contractor, or construction site.

    Depending on the project, a construction insurance program may include:

    Commercial General Liability

    Commercial general liability, often called CGL, helps respond to claims involving bodily injury or property damage caused to others during business operations.

    For example, it may address a third-party claim if a visitor is injured at a site or construction activity damages neighbouring property. CGL generally does not replace builder’s risk because it is designed primarily for liability, not damage to the project itself.

    Wrap-Up Liability

    A wrap-up policy can provide project-specific liability protection for multiple parties, such as the owner, general contractor, and subcontractors.

    This structure may be suitable for larger or more complex projects because it can help create a coordinated liability program. Contract requirements, project size, and the number of parties involved will influence whether it is appropriate.

    Contractor’s Equipment Insurance

    Contractors may need protection for tools, machinery, generators, lifts, and other equipment used across different locations.

    This coverage is separate from insurance for the building under construction. A project can have adequate builder’s risk while a contractor’s equipment remains underinsured or excluded.

    Professional Liability

    Architects, engineers, designers, and other professionals may need professional liability or errors and omissions coverage for claims arising from professional services.

    Builder’s risk is not a substitute for this protection. Physical damage to a building and financial loss caused by professional advice are different insurance exposures.

    Environmental or Pollution Liability

    Excavation, demolition, mould, fuel, contaminated soil, and other environmental exposures may require specialized coverage.

    The need for environmental insurance depends on the property, construction methods, history of the site, materials involved, and contractual obligations.

    Excess or Umbrella Liability

    Larger projects may require liability limits above those provided by a primary CGL or wrap-up policy. Excess or umbrella liability can provide an additional layer of protection, subject to its terms and exclusions.

    Know When You May Need Each Policy

    Choose Builder’s Risk When the Project Itself Is the Concern

    Builder’s risk may be appropriate when you need to protect:

    • A new building before completion
    • A major renovation or addition
    • Materials stored at or near the site
    • Temporary works and construction-related property
    • Certain soft costs following an insured loss

    If your main question is, “What happens if the building or materials are damaged during construction?”, builder’s risk is likely the starting point.

    Build a Broader Construction Program for Wider Protection

    A broader construction insurance program may be more suitable when you need to address:

    • Claims from members of the public
    • Risks involving contractors and subcontractors
    • Tools, machinery, and mobile equipment
    • Design or professional services
    • Pollution or environmental exposures
    • Large liability limits
    • Delays that affect financing, occupancy, or revenue

    If your question is, “Are the project, people, operations, equipment, and third parties protected?”, you may need more than builder’s risk alone.

    Compare Builder’s Risk in Alberta, BC, and Ontario

    The fundamental purpose of builder’s risk is similar across Alberta, British Columbia, and Ontario: it is intended to protect the physical project during construction, subject to the policy’s terms.

    However, project requirements can vary based on:

    • Construction type and project value
    • Location and exposure to weather, wildfire, flood, or theft
    • Contract wording
    • Financing or lender requirements
    • Municipal approvals and permits
    • The responsibilities assigned to the owner, contractor, and subcontractors
    • Provincial workplace and construction requirements
    • Whether the property is residential, commercial, industrial, or multi-unit

    For example, a lender or project owner may require evidence of builder’s risk before releasing funds. A general contractor may also need ongoing CGL, contractor’s equipment, commercial auto, and other business coverage.

    In Alberta, new home warranty requirements are separate from builder’s risk. A warranty may address certain defects after completion, while builder’s risk generally addresses physical loss or damage during construction. Similar distinctions should be considered for projects in BC and Ontario.

    For local guidance, Alliance Insurance Associates can help you review Builder’s Risk AB, Builder’s Risk BC, or Builder’s Risk ON options based on your project and responsibilities.

    Complete construction insurance program with liability, equipment, and professional coverage

    Avoid These Common Coverage Gaps

    Construction projects can change quickly. A policy arranged at the beginning may no longer reflect the risk several months later.

    Review your insurance when:

    • The project value increases
    • Construction is delayed
    • The completion date changes
    • Materials are stored off-site
    • The building will remain vacant longer than expected
    • The scope of work expands
    • A new contractor or subcontractor joins the project
    • The ownership structure changes
    • The building is partially occupied
    • Construction changes from renovation to demolition or rebuilding

    Also confirm who is responsible for arranging and paying for each policy. Depending on the contract, builder’s risk may be arranged by the owner, developer, or general contractor. Responsibility should be clear before work begins.

    Ask contractors and subcontractors for current certificates of insurance, but remember that a certificate is not a complete review of the policy. Limits, exclusions, endorsements, and named insureds all matter.

    Make an Informed Construction Insurance Decision

    The simplest way to think about the difference is:

    • Builder’s risk protects the project’s physical work in progress.
    • Construction insurance protects the broader network of risks surrounding the project.

    For many projects, the best approach is not choosing one instead of the other. It is coordinating builder’s risk with liability, equipment, professional, environmental, and other relevant coverages.

    Every project is different. A small renovation, a commercial development, a multi-unit building, and a contractor’s annual operations can require very different insurance solutions.

    Insurance consultant and project owner reviewing construction coverage and blueprints

    Speak With a Construction Insurance Consultant

    At Alliance Insurance Associates, we help individuals and businesses make informed insurance decisions with practical risk management guidance.

    Our team can help you review your project location, construction value, contract requirements, timeline, contractors, materials, and potential liability exposures. We can also help compare tailored Construction Insurance AB, Construction Insurance BC, and Construction Insurance ON solutions through our access to insurance providers and carriers.

    Before construction begins, request a commercial insurance review so you can move forward with greater clarity, confidence, and control.
  • Home and Auto Insurance Savings Checklist for Alberta

    Home and Auto Insurance Savings Checklist for Alberta

    A home and auto insurance savings checklist is a structured review of your two policies that identifies missed discounts, outdated information, and preventable risks before your renewal date. In Alberta, working through one properly can recover several hundred dollars a year, because our market prices by postal code, by hail exposure, and by a driving grid that most policyholders have never seen.

    Key Takeaways

    • Alberta homeowners’ insurance premiums rose 391.6% between December 2005 and December 2025, according to Statistics Canada data released in June 2026.
    • Bundling home and auto typically saves 5% to 20%, but it is rarely the largest saving available to an Alberta household.
    • The Good Driver Rate Cap protects clean records, and switching insurers can make you ineligible. That changes the usual “shop around every year” advice.
    • Care-First arrives January 1, 2027, with an estimated average saving of $231 per vehicle on full coverage and $366 on basic.
    • Hail is the single biggest cost driver on Alberta home policies. Roofing class and deductible structure matter more than any discount code.

    Why Alberta Premiums Behave Differently

    Most national insurance advice is written for Ontario. Alberta is a different market, and the differences are where the money is.

    Factor

    How it works in Alberta

    Auto market

    Private, regulated by the Alberta Automobile Insurance Rate Board, with more than 40 insurers writing personal vehicles

    Home market

    Largely deregulated, so insurers price aggressively by postal code and risk features

    Catastrophe exposure

    Alberta has recorded a major hailstorm every year for a decade, totalling roughly $8 billion in damage

    Average home premium

    Roughly $1,800 to $2,000 a year, up about 11.9% year over year in Q2 2026

    The August 2024 Calgary hailstorm produced more than 130,000 claims and about $3.25 billion in insured losses, making it the second-costliest disaster in Canadian history behind the 2016 Fort McMurray wildfires. That event is still working its way through Calgary and Edmonton renewal pricing.

    Step 1: Update What Changed Since Your Last Renewal

    Insurers price based on the file they have. If your file is stale, you are either overpaying or underinsured, and sometimes both.

    Work through these six items first:

    1. New valuables. Jewellery, tools, bikes, cameras, and high-end electronics often sit under a per-category sublimit. Anything valuable usually needs to be scheduled separately.
    2. Renovations. A new roof, updated wiring, replaced plumbing or a new furnace can lower your premium. A finished basement or a major addition raises your rebuild cost, so coverage needs to move up with it.
    3. Mileage. Hybrid work, a shorter commute or a second vehicle sitting idle all change your rating. Under 10,000 km a year usually opens a low-mileage or telematics option.
    4. Drivers on the policy. A newly licensed teen, a partner who now drives more, or a roommate who moved out all shift the rate.
    5. Rental or secondary use. Renting out a basement suite or listing a room changes your policy category entirely.
    6. Contact and mortgage details. Small, but a mortgage discharge can qualify you for a mortgage-free discount at some insurers.

    Ten minutes here is usually the highest return on effort in the entire checklist. If you are unsure what your current policy actually covers, our guide to what home insurance covers in Alberta breaks down the standard sections.

    Step 2: The Discounts Most Albertans Are Not Claiming

    Discounts vary by insurer and none are automatic. You have to qualify and ask.

    Discount

    Applies to

    Typical saving

    What to have ready

    Multi-policy bundle

    Both

    5% to 20%

    Both policy numbers

    Multi-vehicle

    Auto

    Up to 15%

    All VINs on one policy

    Winter tires

    Auto

    2% to 5%

    Purchase receipt or installer invoice

    Telematics / usage-based

    Auto

    Up to 25%

    Smartphone or plug-in device

    Approved driver training

    Auto

    Varies

    Course completion certificate

    Conviction free

    Auto

    Varies

    Clean abstract

    Anti-theft device

    Auto

    Varies

    Installation record

    Retiree or student

    Auto

    Varies

    Proof of status

    Monitored alarm

    Home

    5% to 15%

    Monitoring contract

    Water leak sensors, sump alarm

    Home

    2% to 10%

    Product details

    Claims free

    Home

    Varies

    Claims history

    Mortgage free

    Home

    5% to 10%

    Discharge statement

    Pay in full annually

    Both

    2% to 5%

    Lump sum capacity

    Non smoker

    Home

    Varies

    Declaration

    Mature homeowner (often 55+)

    Home

    Varies

    Date of birth

    Association, alumni or employer group

    Both

    Varies

    Membership number

    Two notes worth more than the table. First, the largest saving in most Alberta households is not a discount at all, it is moving to a better-priced insurer for that specific risk. Identical coverage can vary by hundreds of dollars between carriers. Second, a higher deductible lowers your premium but transfers risk to you, and in a hail zone that trade is less attractive than it looks.

    For deeper detail on the auto side, see our list of ways to save on your auto insurance and our top tips for saving on home insurance.

    Step 3: The Alberta Rate Rules That Decide Your Premium

    This is the section national comparison sites skip, and it is where a broker earns their keep.

    The Grid and at-fault claims

    Alberta uses a grid rating system that sets a maximum basic premium based on driving history. New drivers start at the bottom. A single at-fault claim can drop you several levels, and the effect follows you for years. That is why very minor damage is sometimes cheaper to pay out of pocket than to claim. If you are unsure how fault gets assigned, our explainer on Direct Compensation for Property Damage covers the mechanics.

    The Good Driver Rate Cap

    The cap limits how much a clean-record driver’s premium can rise. To qualify in 2026, you need:

    • No at-fault claims in the past six years
    • No criminal convictions in the past four years
    • No major convictions in the past three years
    • No minor convictions in the past three years

    Here is the part almost nobody mentions. Certain changes can end your eligibility, including moving to a higher-risk area, adding a higher-risk driver, changing vehicles or switching insurers. So the standard advice to shop every year needs a caveat in Alberta. If you are capped and your renewal increase is small, staying put can beat a slightly cheaper quote elsewhere. If your increase is steep, the cap is worth less than the switch. Run the numbers rather than following a rule of thumb.

    What changes on January 1, 2027

    Alberta introduces the Care-First auto insurance system, which moves injury claims toward faster, more predictable benefits and away from litigation. An independent actuarial report estimates average savings of $231 per vehicle for full coverage and $366 for basic coverage.

    A new rate cap arrives with it, in two parts:

    • 5% cap on insurers across their entire book of business per year
    • 10% cap on individuals at renewal from an insurer’s rate change

    The 10% cap does not protect you from increases caused by your own risk profile. A new at fault accident, a new conviction, a vehicle change or a coverage change can all push your premium past it. We cover the broader picture in our overview of what changes for Alberta insurance in 2027.

    Step 4: Hail, Water and Wildfire

    Preventing a claim beats winning one. Alberta’s loss profile is dominated by weather, and three items carry real premium weight.

    Hail. Impact-resistant roofing, often rated Class 4, earns credits with several insurers and reduces the chance of a claim in the first place. In Calgary’s north and northwest, the payback period on premium savings alone is frequently in the seven-to-ten-year range, before counting the deductible you avoid. Also check whether your policy now carries a separate or percentage-based hail and wind deductible. Many Alberta policies do, and homeowners often discover it mid-claim.

    Water. Overland water and sewer backup are usually endorsements, not standard coverage. Test your sump pump before spring melt, install a backwater valve, and keep downspouts discharging well away from the foundation. The Insurance Bureau of Canada publishes practical guidance on both.

    Wildfire. If you are in or near an interface zone, FireSmart measures such as non-combustible roofing, ember-resistant vents and a cleared perimeter affect both insurability and price.

    Winter. Keep heat consistent and insulate exposed pipes, clear gutters and roof edges to stop ice dams, shovel and salt promptly because slip and fall liability is yours, and fit true winter tires rather than all-season. Cold also kills batteries, and poor visibility causes more claims than ice does.

    Step 5: Time Your Renewal Properly

    Most people shop three days before renewal, which is too late to do it well.

    Timing

    Action

    60 days out

    Request your renewal declaration and current declarations page

    45 days out

    Update your broker on everything from Step 1

    30 days out

    Compare the market on identical limits and deductibles

    14 days out

    Confirm discount eligibility in writing

    Renewal day

    Verify the new policy is bound before the old one lapses

    A real example

    A Sherwood Park couple with a 2019 SUV and a 2004 bungalow came to us paying $4,380 combined. Nothing exotic changed. We bundled with a carrier priced better for their postal code, added winter tires and a monitored alarm, enrolled one driver in telematics, and raised the water deductible while keeping the hail deductible flat. Combined premium landed near $3,540. The single largest component was the carrier change, not the discounts.


    Common Problems and How to Solve Them

    Challenge

    Practical solution

    Premium jumped with no claims

    Ask which rating factor changed, then compare the market before assuming it is universal

    Hail damage, but afraid to claim

    Get an independent roof assessment first, then weigh repair cost against your actual deductible

    Told you are ineligible for coverage

    An independent broker can access markets a single insurer cannot

    Bundle quoted higher than two separate policies

    It happens. Bundling is a discount, not a guarantee of the lowest total

    Where This Is Heading

    Expect three shifts over the next two years. Care-First should ease auto pricing pressure from 2027 onward, though the effect will vary by driver. Home insurers will keep pricing hail granularly, which means roofing material becomes a pricing input rather than a maintenance decision. And telematics is moving from an optional discount to a default expectation for younger drivers.

    Alberta’s regulator publishes approved rate filings and premium data by postal code, so you can check whether your increase reflects the market or just your insurer. That transparency is new and worth using.

    Frequently Asked Questions

    How much does bundling home and auto save in Alberta? 

    Usually 5% to 20%, depending on the insurer and products combined. Always compare the bundled total against two separate policies, because the discount does not always produce the lowest overall price.

    Can I keep the Good Driver Rate Cap if I switch insurers? 

    Not necessarily. Switching insurers is one of the changes that can end eligibility, along with moving to a higher-risk area, adding a higher-risk driver, or changing vehicles. Confirm the impact before you move.

    Will Care-First actually lower my premium in 2027? 

    An independent actuarial report estimates average savings of $231 per vehicle for full coverage and $366 for basic. Pricing stays risk-based, so your result depends on your own record and vehicle.

    Is a higher deductible worth it if I live in a hail zone? 

    Only if you can comfortably pay it. Check whether your policy applies a separate percentage-based hail deductible, which can be far larger than your standard one.

    Does a hail claim raise my home insurance premium?

    It can, and it may also affect claims-free discount eligibility. Weigh the repair cost against your deductible before filing.

    How often should I review both policies? 

    Once a year at renewal, plus after any renovation, move, vehicle change, or new driver.

    Do winter tires actually earn a discount in Alberta? Most insurers offer a modest credit for true winter tires, not all-season or all-weather. Keep the invoice, since insurers ask for proof.

    Start With One Section

    You do not need to do all of this in one sitting. Update what changed, then check the discount table against your declarations page. Those two steps alone will find money for most households.

    If you want a second set of eyes, Alliance Insurance has been placing home and auto coverage across Edmonton, Calgary, and British Columbia since 2004. As independent brokers, we compare multiple insurers rather than defending one, which matters more in a hail-exposed market than it does anywhere else in the country. Learn more about our brokerage, explore our Edmonton home insurance coverage, or request a quote, and we will run your renewal against the market.

  • Small Business Insurance in Alberta: Cost, Coverage and Legal Requirements

    Small Business Insurance in Alberta: Cost, Coverage and Legal Requirements

    Small business insurance in Alberta is a package of policies that pays for property damage, liability claims, lost income and legal costs when something goes wrong in your business. Most Alberta owners build it around three pieces: commercial general liability, commercial property, and business interruption. Then they add coverages that match how they actually operate, such as cyber, errors and omissions, or commercial auto.

    Almost nobody explains the part that trips owners up, so we will start there. Business insurance is not required by Alberta statute for most companies. Several other things are.

    Key takeaways

    • General business insurance is not mandated by Alberta law, but commercial auto, WCB registration and some professional liability requirements are.
    • WCB-Alberta coverage is not something a broker sells you, and it does not automatically cover you as the owner.
    • Basic $2 million commercial general liability commonly runs from roughly $400 to $1,500 per year in Alberta, with $450 often quoted as a benchmark.
    • Landlords, lenders and general contractors frequently require coverage before you can sign, which makes insurance compulsory in practice long before the law gets involved.
    • Alberta carries an outsized share of Canada’s severe weather losses, which affects both what you pay and how your property limits should be set.

    What is small business insurance, and how is it different from commercial insurance?

    The terms get used interchangeably, and that causes real confusion when you are shopping. Here is the practical distinction.

    Home-based businessSmall businessCommercial / mid-market
    Where it operatesYour residenceLeased or owned commercial spaceMultiple sites or high revenue
    Usual routeHome policy endorsement, or a standalone liability policyA business owners package (BOP)A layered program built coverage by coverage
    Typical trigger to move upClients visiting, or inventory on siteHiring staff, signing a leaseFleet, payroll over a few million, complex contracts

    One point worth being blunt about: a standard Alberta home policy generally excludes business exposure. If clients come to your house, or you hold stock in the garage, your home policy is probably not doing what you assume it is. Our commercial insurance overview walks through where the line sits.

    Is business insurance legally required in Alberta?

    No, not as a general rule. Alberta does not require most businesses to carry insurance in order to operate. But four situations create genuine obligations, and three of them catch new owners off guard.

    What the law actually requires

    1. Commercial auto. Any vehicle used for business needs a commercial auto policy. Alberta requires every auto policy to include third-party liability, accident benefits, and direct compensation for property damage. If you are unclear on that last one, our explainer on direct compensation for property damage covers how it works after a collision.
    2. WCB-Alberta registration, if you employ workers in a compulsory industry.
    3. Professional liability, for regulated professions where a governing body requires proof before licensing.
    4. Contractual requirements, which are not law but bind you just as tightly.

    WCB-Alberta: the piece most guides get wrong

    This is where we see the most costly misunderstandings, so read this section twice.

    Workers’ compensation in Alberta is administered by WCB-Alberta. It is not a product an insurance broker places. If someone tells you they can sell you workers’ compensation, something has been lost in translation.

    What you need to know:

    • If you operate in a compulsory industry, you must open a WCB account within 15 days of hiring your first worker.
    • Some industries are exempt. Exempt employers can still apply voluntarily to protect their workers.
    • As the owner, director or partner, you are not automatically covered. Only your workers are. Covering yourself requires optional personal coverage, purchased separately. For 2026, wage-loss coverage runs from a $34,200 minimum to a $110,900 maximum.
    • Before you pay a subcontractor, request a clearance letter. If a sub has no coverage of their own, WCB may treat them as your worker, and their injury becomes your account’s problem.

    Commercial general liability does not substitute for any of this. They cover different things.

    What your contracts require

    Read the insurance clause in your lease before you shop, not after. Alberta commercial leases routinely demand $2 million or $5 million in general liability, plus an additional insured endorsement naming the landlord. General contractors ask for the same from subtrades. Municipal vendor programs ask for certificates of insurance with specific wording.

    If you sign first and insure second, you may find your quote does not meet the clause you already agreed to.

    How much does small business insurance cost in Alberta?

    Published broker figures across the province cluster in a fairly consistent band:

    CoverageTypical Alberta range
    Basic CGL, $2 million limitAbout $400 to $1,500 per year, with $450 commonly cited as a starting benchmark
    Basic CGL, $1 million limitRoughly $40 to $150 per month
    Full small business packageCommonly $300 to $1,700 per year for lower-risk operations

    Treat these as orientation, not a quote. Two bookkeepers on the same street can pay different premiums.

    What actually moves your premium

    • Industry classification and the work you physically perform
    • Annual revenue and payroll
    • Property values, including tenant improvements and inventory
    • Limits, deductible and any sublimits
    • Claims history over the past five years
    • Documented risk controls, such as monitored alarms, sprinklers and a written safety program

    How to reduce it without gutting your coverage

    Raise your deductible if your cash flow can absorb it. Bundle policies with one insurer. Install and document loss prevention. Pay small losses yourself rather than papering a claim that follows you for years. Review annually, because most businesses outgrow their original limits within about three years and never notice.

    The cheapest quote is frequently the one that fails to meet your lease requirement. A broker’s job is to catch that before you bind, which is why choosing the right broker for your business matters more than shaving $80 off a premium.

    What each coverage actually does

    CoverageWhat it responds toWho needs it most
    Commercial general liabilityThird-party injury, property damage, personal and advertising injuryNearly every business
    Commercial propertyBuilding, contents, stock, equipment, tenant improvementsAnyone with a physical location or gear
    Business interruptionLost income and ongoing expenses during a forced closureRetail, restaurants, manufacturing
    Errors and omissionsClaims that your advice or service caused a client financial lossConsultants, bookkeepers, designers, IT
    Cyber liabilityBreach response, ransomware, funds transfer fraudAnyone holding client data or taking payments
    Equipment breakdownMechanical and electrical failure, and resulting spoilageFood service, trades, clinics
    Commercial autoVehicles, tools in transit, hired and non-owned exposureContractors, delivery, mobile services

    Cyber deserves a specific mention. Smaller firms are frequently the easier target precisely because they lack enterprise security tooling, and the recovery cost tends to land harder. Our guide to cyber liability insurance explains what breach response actually pays for.

    The Alberta risk picture and why your property limits matter

    This province is not an average insurance market. According to the Insurance Bureau of Canada, 2024 was the costliest year on record for severe weather losses in Canada at $8.5 billion, and roughly half of that damage occurred in Alberta. The August 2024 Calgary hailstorm alone became the second-costliest insured event in Canadian history. IBC reported that severe weather losses again exceeded $2.4 billion nationally in 2025, including another July hailstorm in Calgary.

    Hail and wind damage are covered by standard business property policies. Two things commonly are not, unless you specifically add them: overland water and sewer backup. Ask about both. Ask about earthquakes if you hold high property values.

    Then check the mechanism that nobody explains. Most property policies carry a coinsurance clause, meaning if you insure your contents for less than a stated percentage of their replacement value, your claim payment gets reduced proportionally even on a small loss. Underinsuring to save on premiums is an expensive mistake.

    Two situations we see repeatedly

    The tenant improvement gap. A restaurant owner insures kitchen equipment and inventory and assumes the landlord’s policy covers the build-out. It usually does not. The lease makes improvements the tenant’s responsibility, and a fire leaves a six-figure hole.

    The subcontractor clearance letter. A general contractor hires a framing crew, pays the invoice, and later learns the crew had no WCB coverage. The injury lands on the GC’s account, and the premium follows for years. A clearance letter request takes minutes.

    Cleaning and janitorial firms hit a third variation, where care, custody and control of a client’s property sits outside standard liability wording. We covered that specifically in our piece on insurance for janitors, maids and cleaning businesses.

    Best practices before you buy

    1. Inventory your assets at replacement cost, not what you paid.
    2. Pull the insurance clause out of every lease and client contract first.
    3. Separate personal from commercial use, especially with vehicles and home offices.
    4. Match limits to contract requirements rather than to the cheapest option.
    5. Confirm your certificate of insurance and additional insured wording say what your landlord asked for.
    6. Review at renewal, and any time revenue, payroll or property values shift materially.

    Have your revenue, payroll, square footage, property values, loss history and lease insurance clause ready. Quotes move much faster with those six items in hand.

    Common challenges, and what to do about them

    ChallengePractical fix
    Premiums rising after catastrophe yearsDocument risk controls, adjust deductibles, review limits annually with a broker
    Not knowing what a contract requiresRead the clause before shopping, and send it to your broker
    Underinsured propertyValue at replacement cost and understand your coinsurance percentage
    Cyber exposure with no IT departmentPair a policy with multi-factor authentication and offline backups
    WCB confusion as an ownerConfirm your industry status and buy personal coverage if you want to be covered

    Where this market is heading

    Three shifts are already visible. Property capacity in hail-exposed parts of Alberta is tightening, which is showing up as higher deductibles and stricter roof requirements rather than outright declines. Insurers are increasingly underwriting cyber on the basis of controls you can prove, so multi-factor authentication is becoming a condition rather than a discount. And instant online binding is expanding for straightforward low-risk classes, while anything involving trades, food service or fleets still needs a human to place properly.

    Frequently asked questions

    Is business insurance mandatory in Alberta? Not generally. Commercial auto is required for business vehicles, WCB registration is required for employers in compulsory industries, and some regulated professions must carry professional liability. Leases and contracts often require coverage regardless.

    How much does small business insurance cost in Alberta? A basic $2 million commercial general liability policy commonly runs from about $400 to $1,500 per year. Full packages with property and business interruption cost more depending on values and industry.

    Is $1 million in general liability enough? It depends on your contracts. Many Alberta leases and subcontractor agreements specify $2 million or $5 million, so check the clause before choosing a limit.

    Does my home insurance cover my home-based business? Usually not. Home policies typically exclude business exposure. You may need an endorsement or, past a certain scale, a standalone commercial policy.

    Do I need WCB coverage if I am the only person in the business? You are not automatically covered as an owner. If you want workers’ compensation benefits for yourself, you need optional personal coverage through WCB-Alberta.

    Does business insurance cover hail damage? Yes, hail and wind are standard perils on commercial property policies. Overland water and sewer backup usually require separate endorsements.

    How quickly can I get covered? Straightforward liability-only risks can often be bound the same day. Packages involving property, fleets or trades typically take a few business days.

    Will one claim raise my premium? Frequently yes, and claims history follows you for about five years. That is why absorbing very small losses yourself can be the cheaper decision.

    Getting the coverage right

    The businesses that get burned are rarely the ones that bought nothing. They are the ones who bought a policy that did not match their lease, their contracts, or what they actually owned. That gap is where a broker earns their fee.

    If you want a straight answer about what your Alberta business needs and what it should cost, request a quote or call our Edmonton or Calgary office. If you are already dealing with a loss, start with our claims process.

  • Direct Compensation For Property Damage (DCPD) Insurance

    Direct Compensation For Property Damage (DCPD) Insurance

    Direct Compensation for Property Damage, or DCPD, is the mandatory Alberta auto coverage that pays to repair or replace your own vehicle when another driver is at fault for a collision. Your insurer handles the claim and cuts the cheque. You never deal with the other driver’s insurance company.

    It has worked this way since January 1, 2022, and most Albertans still find out about DCPD the hard way: standing on the shoulder of Whitemud Drive, wondering who they are supposed to call.

    Key takeaways

    • DCPD covers your vehicle, its contents, and loss of use when you are not at fault. Your own insurer pays.
    • It is mandatory on Alberta policies and comes with a $0 deductible by default.
    • If you are partly at fault, DCPD pays your not-at-fault share. The rest falls to optional collision coverage.
    • DCPD does not respond to hit-and-runs, uninsured vehicles, theft, hail, or injuries.
    • Care-First arrives January 1, 2027, and changes the injury side of your policy. Physical damage coverage stays as it is.

    What DCPD actually covers

    The province did not change what gets paid for. It changed who pays. Before 2022, you chased the other driver’s insurer for your repairs. Now you call your own.

    Covered under DCPDNot covered under DCPDCoverage you need instead
    Repair or replacement of your vehicleYour at-fault share of the damageCollision or all perils
    Damage to contents inside the vehicle (limits apply, commonly $20,000)Contents carried for rewardCommercial cargo coverage
    Loss of use: rental car, taxi, transit while repairs happenHit-and-run or unidentified driverCollision, or unidentified motorist endorsement
    Your not-at-fault percentage in a shared-fault crashCollisions with uninsured vehiclesCollision, or Alberta’s Motor Vehicle Accident Claims Program
    Theft, fire, hail, vandalism, falling objectsComprehensive or specified perils
    Injury to you or your passengersSection B accident benefits

    DCPD is mandatory across nearly every vehicle class in Alberta, including passenger vehicles, motorhomes and RVs, ATVs, commercial vehicles and fleets. If you ride, the same logic carries over to motorcycle insurance, where repair costs and rate groups behave differently than they do on a sedan.

    Who pays after a collision: three real scenarios

    Fault is not all-or-nothing in Alberta. It is assigned in percentages, and those percentages decide which part of your policy responds.

    You are 0% at fault

    Someone rear-ends your truck at a red light on Macleod Trail. Repairs run $10,000.

    Your insurer pays the full $10,000 under DCPD. You pay no deductible. Because you carry none of the fault, the claim does not count against your claims history.

    You are 25% at fault

    Same $10,000 in damage, but the adjuster assigns you a quarter of the blame. Assume a $500 collision deductible.

    • DCPD pays your 75% not-at-fault share: $7,500
    • Collision pays your 25% share, less 25% of your deductible: $2,375
    • You pay 25% of your deductible: $125

    The deductible gets prorated to your share of fault. That surprises people, and it is one of the more useful things to understand about how your auto insurance coverage fits together.

    Without collision coverage, that same driver eats the full $2,500.

    You are 100% at fault

    DCPD does nothing here. Collision or all perils pays, minus your full deductible. No collision coverage means the repair bill is yours.

    Will a DCPD claim raise your premium?

    If you are 100% not at fault, using your DCPD coverage will not hurt your claims history or push your rate up. The Automobile Insurance Rate Board is explicit about this, and it is the single most common worry brokers hear.

    Carry any meaningful share of the fault and the picture changes. Insurers generally treat a claim where you hold 25% or more of the blame as an at-fault claim, which affects both your basic and optional premiums. Commercial auto is less predictable than personal auto on this point, so fleet operators should ask their broker directly.

    Why your premium now depends on your own vehicle

    Here is the shift almost nobody explains to drivers. Under the old system, your property damage premium was priced on the average cost of repairing whatever car you might hit. Nobody could know what that was.

    Now your insurer pays to fix your vehicle, so it prices your DCPD premium using vehicle rate groups based on your specific make, model, year, repair cost and claims frequency. Buy a truck with $4,000 headlamp assemblies and expect that to show up on renewal. Drivers looking at ways to save on auto insurance should factor repair cost into the purchase decision, not just the sticker price.

    Deductibles and the DCPD delete option

    DCPD arrives with a $0 deductible. You can elect one in exchange for a lower premium, and Alberta’s Superintendent of Insurance also released a DCPD deletion endorsement that some insurers offer.

    Deleting DCPD may make sense if:

    • Your vehicle is old with low book value
    • You own it outright with no lender requirements
    • You could comfortably absorb a total loss out of pocket tomorrow

    Do not delete DCPD if:

    • The vehicle is leased or financed, since lenders almost always require physical damage coverage
    • Replacing it out of pocket would strain you
    • You drive high-traffic corridors daily

    The trap is timing. Your finances today are not your finances the morning someone runs a light. Talk it through with your broker before signing an endorsement that removes coverage.

    How fault gets decided, and what to do if you disagree

    Alberta’s DCPD Regulation sets out fault determination rules covering most collision scenarios with diagrams. Your adjuster works from statements, police reports, the estimator’s findings, the Traffic Safety Act, and past court decisions.

    One detail catches people off guard: fault must be assigned without reference to weather, visibility, pedestrian actions, or the exact point of contact. Icy roads do not reduce your share.

    Two limits worth knowing:

    1. You cannot sue the other driver for your vehicle damage, contents, or loss of use. Section 585.1(7) of the Insurance Act bars it.
    2. Disputes over the amount of your settlement go through a mandatory Dispute Resolution Process, not the courts.

    Fault percentage disputes are a different matter and can proceed under ordinary rules of law. Push back in writing, ask for the specific rule applied, and involve your broker early.

    Does DCPD change under Care-First in 2027?

    Short answer: no, not the part that pays for your car.

    Alberta moves to the Care-First model on January 1, 2027, following Bill 47. The reform overhauls injury claims: unlimited medical and rehabilitation benefits, income replacement to age 65, a permanent impairment benefit, and a new tribunal instead of lawsuits.

    Physical damage coverage carries over unchanged. DCPD, collision and comprehensive keep working the way they do now.

    If your accident happens before January 1, 2027, your claim stays under the current system even if it drags into 2027. The province has published draft form amendments, so wording will shift, but the mechanics of a not-at-fault repair claim will feel familiar.

    After a not-at-fault collision: the practical sequence

    1. Check for injuries and move to safety.
    2. Photograph both vehicles, plates, damage, and the scene layout before anything moves.
    3. Get the other driver’s name, licence, insurer and policy number. Without an identified vehicle, DCPD cannot respond.
    4. Report to police or a collision reporting centre where required.
    5. Call your own insurer or broker, not the other driver’s company.
    6. Ask your adjuster for your assigned fault percentage in writing.
    7. Confirm whether loss of use covers a rental before you book one.

    Fast, documented reporting is what separates a two-week repair from a two-month one. Our claims team walks Alberta clients through this daily, and the advantages of solid auto coverage show up most clearly in the first 48 hours.

    Frequently asked questions

    Is DCPD mandatory in Alberta? Yes. It has been mandatory on all Alberta auto policies since January 1, 2022, though a deletion endorsement is available through some insurers.

    Does DCPD cover hit-and-run damage? No. DCPD requires an identified vehicle and driver. Hit-and-run damage falls to collision coverage or an unidentified motorist endorsement.

    Does DCPD cover theft or hail? No. Those are comprehensive or specified perils claims.

    Is there a deductible on DCPD? It defaults to $0. You can elect a deductible for a lower premium if your insurer offers one.

    Will my rate go up if I am not at fault? No. A 100% not-at-fault DCPD claim does not adversely affect your claims history or premium.

    What if the other driver is uninsured? DCPD does not apply. You would rely on collision coverage or Alberta’s Motor Vehicle Accident Claims Program.

    What happens if I crash in BC or Saskatchewan? Claims are generally governed by the law where the accident happens. BC, Saskatchewan and Manitoba use public insurers and do not run DCPD systems.

    Does DCPD apply to commercial vehicles and fleets? Yes, including commercial vehicles, fleets, RVs, motorcycles and ATVs.

    Which provinces use DCPD? Alberta, Ontario, Quebec, Nova Scotia, New Brunswick, Newfoundland and Labrador, and Prince Edward Island.

    Where this leaves you

    DCPD removed the worst part of a not-at-fault collision: arguing with a stranger’s insurance company. What it did not remove is the need to check whether the rest of your policy covers the gaps, because DCPD alone leaves you exposed to theft, hail, hit-and-runs and your own at-fault share.

    Pull out your declaration page and look for three lines: your DCPD deductible, whether you carry collision, and whether you carry comprehensive. If any of those surprises you, that is worth a conversation.

    Alliance Insurance brokers work with Alberta drivers in Edmonton and Calgary and with clients in British Columbia. Request a quote or get in touch and we will read your policy with you.

    Suggested Image Ideas

    #ImageAlt textPlacement
    1Hero: damaged front quarter panel of a vehicle on an Alberta road, winter lightAlberta driver inspecting collision damage covered by DCPD insuranceTop of article
    2Flowchart: “Who pays for your vehicle?” branching on 0% / partial / 100% fault into DCPD, collision, out of pocketFlowchart showing whether DCPD or collision coverage pays based on fault percentage in Alberta“Who pays after a collision” section
    3Bar graphic of the $10,000 / 25% fault example split into $7,500 DCPD, $2,375 collision, $125 deductibleBreakdown of a $10,000 Alberta DCPD claim at 25 percent faultUnder the 25% at fault scenario
    4Three-column comparison card: DCPD vs collision vs comprehensiveComparison of DCPD, collision and comprehensive auto insurance coverage in Alberta“What DCPD actually covers”
    5Timeline: Jan 2022 DCPD introduced, May 2025 Bill 47 royal assent, Jan 1 2027 Care-First beginsTimeline of Alberta auto insurance reform from DCPD in 2022 to Care-First in 2027Care-First section
    6Broker at a desk reviewing a declaration page with a clientAlberta insurance broker reviewing DCPD coverage on a client’s auto policyConclusion / CTA


  • What Does Home Insurance Cover in Alberta?

    What Does Home Insurance Cover in Alberta?

    Home insurance in Alberta covers four things: the structure of your house, the belongings inside it, your legal liability if someone is hurt on your property, and your living costs if you cannot stay in your home after a covered loss. What it does not automatically cover is water backing up through your drains, water flowing in from outside, or an earthquake. Those need separate add-ons.

    That gap catches thousands of Albertans every year, usually in a flooded basement at two in the morning.

    Key Takeaways

    • Every standard policy includes dwelling, detached structures, contents, additional living expenses, and personal liability.
    • Your policy form (comprehensive, broad, basic, or no frills) decides what “covered” actually means.
    • Sewer backup and overland water are optional. If you never asked for them, you almost certainly do not have them.
    • Contents coverage caps common valuables. Jewellery is often limited to $6,000 total, cash to a few hundred dollars.
    • Alberta premiums climbed 11.9% year over year in Q2 2026, the steepest rise in Canada, driven by hail, wildfire, and rebuild costs.

    What Is Home Insurance?

    Home insurance is a contract that pays to repair or replace your property after a sudden, accidental loss, and defends you if someone holds you legally responsible for injury or damage.

    It is not legally required in Alberta the way auto insurance is. It is effectively required if you have a mortgage, because lenders make it a condition of financing. The Financial Consumer Agency of Canada outlines the basics for consumers, and the Alberta Superintendent of Insurance publishes provincial guidance.

    Homeowners without a mortgage are the most commonly underinsured group in the province. Nobody is checking their coverage for them.

    The Five Coverages in Every Alberta Policy

    1. Your Home’s Structure

    This is your dwelling coverage: walls, roof, foundation, attached garage, deck, plumbing, wiring, and built in fixtures.

    The limit should reflect what it costs to rebuild, not what your house would sell for. Alberta construction costs have risen sharply since 2020, and policies written before then are frequently short by tens of thousands of dollars.

    2. Detached Structures

    Sheds, fences, detached garages, gazebos. Coverage is usually capped at roughly 10% of your dwelling limit. If you built a $60,000 detached shop behind a $400,000 house, do the math before you assume you are covered.

    3. Personal Belongings

    Furniture, electronics, clothing, appliances, tools. Typically 50% to 70% of your dwelling limit. This is where sub limits bite, and we cover those below.

    4. Additional Living Expenses

    If a covered loss makes your home unlivable, this pays for hotels, meals, storage, and pet boarding during repairs. Alberta wildfire evacuations have triggered this coverage for entire communities at once.

    5. Personal Liability

    Usually $1 million or $2 million. It covers legal defence and settlements if a guest is injured on your property or your dog bites someone. It follows you off your property too, which surprises most people.

    Coverage at a Glance

    CoverageTypical LimitCommon Sub Limit
    DwellingFull rebuild costNone
    Detached structures~10% of dwellingNone
    Contents50–70% of dwellingSee below
    Jewellery and watchesWithin contents$6,000 total
    Cash and securitiesWithin contents$200–$500
    BicyclesWithin contents$1,000–$2,000
    Business equipment at homeWithin contents$2,500–$5,000
    Personal liability$1M–$2MNone
    Additional living expenses20–30% of dwellingTime limited

    These are industry typical figures, not guarantees. Your declarations page is the only document that tells you your actual numbers.

    Policy Forms: Why Two Quotes Are Rarely Comparable

    The Insurance Bureau of Canada classifies home policies into four forms. This distinction changes the meaning of every section above.

    FormBuildingContentsBest For
    ComprehensiveAll risk, except stated exclusionsAll riskMost homeowners
    BroadAll riskNamed perils onlyBudget conscious owners
    Basic (named perils)Listed perils onlyListed perils onlyCottages, renovations
    No frillsLimitedLimitedHomes failing standard underwriting

    Under a named perils policy, you have to prove a listed peril caused the loss. Under comprehensive, the insurer has to prove an exclusion applies. That reversal matters enormously at claim time.

    What Home Insurance Does Not Cover

    Never covered: wear and tear, poor maintenance, rust and corrosion, rodent or insect damage, mould from an ongoing leak, intentional damage, and war.

    Excluded but available as an add on: sewer backup, overland water, earthquake, oil tank spills, and short term rental activity.

    Covered but capped: everything in the sub limit column above.

    One principle trips people up more than any other: negligence voids claims. Ignore a known leak or let your gutters back up into the foundation, and the resulting damage is your problem.

    Water Damage: Where Alberta Policies Have a Hole

    Water is the most common property claim in Canada. Canadian insurers paid roughly $3.1 billion in water damage claims in 2023 alone.

    Source of WaterUsually Covered?What You Need
    Burst pipe or appliance leakYesStandard policy
    Sewer or drain backupNoSewer backup endorsement
    Overland water (rain, snowmelt)NoOverland water endorsement
    Groundwater seepageNoOften uninsurable

    Real world example. A sewer backup endorsement typically costs between $30 and $100 a year. The average sewer backup claim in Canada runs $20,000 to $45,000. That is one of the strongest value propositions in the entire policy, and most homeowners decline it because nobody explained the difference.

    During the 2013 Alberta floods, which produced roughly $1.7 billion in insured losses, overland flood coverage did not exist in Canada at all. It does now. Ask for it by name.

    Hail, Wildfire, and Winter

    Hail is generally covered under dwelling, but two things need checking: cosmetic damage exclusions, and separate wind and hail deductibles, both of which have spread across the Alberta market. Several carriers offer 20% to 40% discounts on the hail portion of your premium for Class 4 impact rated roofing.

    Wildfire is covered as fire. Disputes arise over smoke damage without direct flame contact. Alberta recorded roughly $4.1 billion in weather related damage in 2024, the highest of any province.

    Frozen pipes are covered when the home was reasonably heated, and denied when it was left unheated and unattended. If you spend winters somewhere warmer, read your vacancy clause.

    What It Costs in Edmonton and Calgary

    CityApproximate Annual Premium
    Edmonton~$1,880
    Calgary~$2,480
    Alberta average~$2,100–$2,500

    Calgary pays more almost entirely because of hail exposure.

    Best practices for lowering your premium:

    1. Bundle home and auto. Our home and auto savings checklist walks through the full list.
    2. Install a backwater valve and a sump pump with battery backup.
    3. Upgrade to impact rated roofing when you replace your roof anyway.
    4. Raise your deductible if you have savings to absorb it.
    5. Review annually. More tips for saving on home insurance are worth a read before renewal.

    Read Your Own Policy in Ten Minutes

    Pull out your declarations page and check six lines: dwelling limit, contents limit, liability limit, deductibles, the endorsement list, and the policy form.

    Then ask your broker five questions:

    1. Is my dwelling limit still accurate at today’s rebuild costs?
    2. Do I have both sewer backup and overland water?
    3. What is my hail deductible, specifically?
    4. Are my valuables scheduled separately?
    5. Is my liability limit still appropriate?

    You can confirm your broker’s licence through the Alberta Insurance Council agent lookup tool. Anyone advising you on this should be registered.

    Special Situations

    • Condo owners. Your policy covers unit improvements, contents, and loss assessment. The corporation’s policy covers the building envelope. The seam between them is where claims get messy.
    • Renters. The landlord’s policy covers neither your belongings nor your liability.
    • Home based business. Standard policies carry minimal equipment coverage, exclude equipment taken off site, and exclude client injury on your property entirely. If clients visit your home, you need commercial coverage.

    Challenges Ahead

    Availability is becoming a real problem in Alberta, not just price. Some Calgary homeowners in high hail postal codes have been declined by multiple carriers before finding coverage at two to three times their previous premium.

    The practical response is mitigation. Impact rated roofs, backwater valves, and updated plumbing and electrical increasingly determine whether you can get a competitive quote at all.

    Future Trends

    Expect three shifts through 2027:

    • Risk based pricing at the property level. Carriers are pricing individual roofs and postal codes rather than broad regions.
    • A federal flood insurance program. Pledged for an April 2026 launch, still unlaunched as of mid 2026, targeting the roughly 10% of Canadian households considered uninsurable for flood.
    • Mitigation discounts becoming standard. Verified upgrades will move from nice to have toward a pricing requirement.

    Frequently Asked Questions

    Is home insurance mandatory in Alberta?

    No, not by law. Mortgage lenders require it as a financing condition, so most homeowners carry it regardless.

    Does home insurance cover hail damage to my roof?

    Usually yes, under dwelling coverage. Check for a separate hail deductible and any cosmetic damage exclusion.

    Is sewer backup covered by a standard policy?

    No. It requires an endorsement, typically $30 to $100 a year against average claims of $20,000 to $45,000.

    Does home insurance cover overland flooding?

    Only with an overland water endorsement. It is separate from sewer backup, and many homeowners need both.

    How much jewellery does home insurance cover?

    Commonly $6,000 in total. Schedule higher-value pieces individually with appraisals.

    Does home insurance cover damage my dog causes?

    Liability generally covers injury your dog causes to others. Damage your dog does to your own property is excluded.

    What is the difference between replacement cost and actual cash value?

    Replacement cost pays for new. Actual cash value subtracts depreciation, which is why an aging roof settled at ACV may not fund a full replacement.

    Get Your Coverage Reviewed

    Most people find out what their policy covers during a claim. That is the worst possible time.

    Bring us your current declarations page, and we will read it against the checklist above, flag the gaps, and tell you what a fix costs. Our Edmonton home insurance brokers work with multiple Alberta carriers, so we can compare endorsement wording across insurers rather than defending one company’s product.

    Call 780-490-0053 in Edmonton, 403-222-0403 in Calgary, or 236-993-0063 in BC. You can also request a quote online or review our claims support process before you need it.

    Figures cited from the Insurance Bureau of Canada, Financial Consumer Agency of Canada, Applied Rating Index (Q2 2026), and published 2026 Alberta rate data. Verify premium figures before publishing.

  • Alberta Cyber Insurance Guide 2026: Costs, Coverage & PIPA Requirements

    Alberta Cyber Insurance Guide 2026: Costs, Coverage & PIPA Requirements

    Cyber insurance is a commercial policy that pays the costs of responding to a data breach, ransomware attack, or system outage, including forensic investigation, customer notification, legal defence, lost income, and extortion demands. Most standard business policies exclude these losses entirely.

    If your Alberta business stores customer information, that matters more than most owners realize. Under Alberta’s Personal Information Protection Act, breach reporting is mandatory when there is a real risk of significant harm, and there is no exemption for small businesses. A three-person dental office carries the same obligation as a national retailer.

    Key Takeaways

    • Standalone cyber policies for Canadian small businesses commonly run between $500 and $3,000 per year. Add-ons to an existing policy cost less but carry much lower limits.
    • Alberta businesses report qualifying breaches to the Office of the Information and Privacy Commissioner of Alberta, not the federal Privacy Commissioner, unless they also operate across provincial borders.
    • Multi-factor authentication is now a baseline requirement. Most Canadian insurers will not quote without it.
    • Commercial general liability and property policies almost always exclude cyber losses. The gap is deliberate, not an oversight.
    • Ransomware coverage usually carries a sublimit, often around half the policy limit.

    Who Actually Needs This Coverage

    Not every business carries the same exposure. A few conditions make cyber coverage a real conversation rather than an afterthought:

    • You accept card or online payments
    • You store customer names, addresses, or payment details digitally
    • Your team works from cloud software, email, or remote access
    • A two-day outage would stop you from serving clients
    • You handle sensitive files in a professional capacity, such as legal, financial, medical, or consulting work
    • A client or government contract requires proof of cyber cover before you can sign

    That last one catches people off guard. Enterprise and public sector buyers increasingly ask for a certificate of cyber insurance during procurement, which turns a nice-to-have into a condition of revenue. If you are reviewing your whole commercial insurance program, this belongs in the same conversation.

    What Cyber Insurance Covers

    Policies are split into two halves.

    First-party coverage pays your own costs:

    • Forensic investigation to find and contain the breach
    • Notifying affected customers and providing credit monitoring
    • Restoring data and rebuilding systems
    • Lost income during the outage, usually capped at 90 to 120 days
    • Ransomware negotiation and payment, subject to sublimits

    Third-party coverage pays when someone comes after you:

    • Legal defence and settlements from customers whose data was exposed
    • Regulatory investigation costs and, in some policies, fines
    • Claims from partners or vendors affected by your breach

    Social engineering and funds transfer fraud are usually optional add-ons rather than core coverage. Given how often invoice redirection scams succeed, that endorsement earns its keep for anyone who pays suppliers by transfer.

    What It Costs in Alberta

    Premiums are calculated, not quoted from a rate card. Underwriters look at three main variables: your gross annual revenue, your industry, and the volume of personal records you hold.

    Business profile

    Typical limit

    Annual premium range

    Cyber endorsement on existing policy

    $50,000 to $100,000

    $100 to $200

    Sole practitioner or small consultancy

    $250,000

    $500 to $1,000

    Retail or trades, under $1M revenue

    $500,000

    $800 to $1,800

    Professional office, 10 to 25 staff

    $1,000,000

    $1,500 to $4,000

    Healthcare, legal, or e-commerce

    $1,000,000+

    $3,000 to $7,500

    Ranges reflect typical Canadian small business pricing and vary by insurer, claims history, and controls in place.

    Put that against the exposure. IBM research puts the average Canadian data breach at around C$5.13 million, with a per-record cost near C$192. A breach touching 3,000 customer files can outrun a decade of premiums.

    What lowers your premium

    Insurers price security posture directly. The controls that move the number the most:

    1. Multi-factor authentication on email, VPN, remote desktop, and admin accounts
    2. Offline or immutable backups, tested on a schedule rather than assumed
    3. Endpoint detection and response, not just consumer antivirus
    4. Documented patching, with critical updates within 30 days
    5. Annual phishing training with recorded completion

    Businesses using a managed IT provider that maintains and documents these controls consistently qualify for better terms than those handling it informally.

    Your PIPA Reporting Obligations

    This is where Alberta differs from most of Canada, and where a lot of otherwise careful owners get caught.

    Alberta is one of three provinces with its own private sector privacy law. Under PIPA, when a breach creates a real risk of significant harm, you must report to the Office of the Information and Privacy Commissioner of Alberta without unreasonable delay and notify affected individuals directly. If your business also operates interprovincially or internationally, you report to the federal Office of the Privacy Commissioner of Canada under PIPEDA as well.

    Two details people miss:

    • There is no small business exemption. PIPA applies to every organization collecting personal information in Alberta during commercial activity, regardless of headcount.
    • You must log every breach, even the ones that do not meet the reporting threshold. An internal record is required either way.

    Notification and legal costs are exactly what cyber policies are built to absorb. Handled without coverage, a mid-sized breach eats a quarter’s profit before you have replaced a single server.


    What Cyber Insurance Does Not Cover

    An honest broker leads with the exclusions.

    Not covered

    Detail

    Acts of war and state-sponsored attacks

    Standard exclusion, increasingly litigated

    Upgrading systems after a loss

    Restoration is covered, improvement is not

    Reputational loss beyond covered PR spend

    Long-term revenue decline is yours

    Fines were uninsurable by law

    Varies by jurisdiction and policy form

    Losses from known unpatched vulnerabilities

    If you disclosed it and did nothing, expect a fight

    One clause deserves specific attention. Many funds transfer fraud sections void coverage if staff change payment details without completing a documented verification step, such as calling the supplier on a previously confirmed number. Write that protocol down before you need it.

    What Happens When You Claim

    A realistic timeline for a ransomware event:

    • Hour 0 to 4. You call the insurer’s 24/7 breach hotline, not your IT contractor. The panel counsel and forensic firm are assigned from here.
    • Days 1 to 3. Containment and scoping. Forensics determines what was accessed and whether personal information was exposed.
    • Days 3 to 10. Legal counsel assesses the real risk of significant harm. Reporting decisions are made.
    • Day 10 to 30. Customer notification, credit monitoring, and regulator correspondence.
    • Day 30 to 90. Business interruption loss is quantified and settled.

    Calling your own vendor first is the most common way businesses damage their own claim. Coverage often depends on using the insurer’s approved panel. Our claims team walks clients through that first hour before it happens, not after.

    Why Applications Get Declined

    Cyber underwriting tightened considerably after the ransomware wave of the early 2020s. Applications commonly fail for:

    • No multi-factor authentication anywhere in the environment
    • Unsupported operating systems still in production
    • Backups stored on the same network as live data
    • Open Remote Desktop Protocol exposed to the internet
    • A prior breach with no documented remediation

    None of these are permanent barriers. Most are fixable in a few weeks, and fixing them before you apply produces a materially better quote than applying and negotiating afterward.

    Cyber Risk Across Alberta Industries

    Sector

    Primary exposure

    Typical priority

    Professional services

    Client file confidentiality

    Third-party liability

    Medical and dental

    Health records under HIA and PIPA

    Notification and regulatory

    Retail and hospitality

    Point of sale and card data

    First-party recovery

    Construction and trades

    Invoice redirection fraud

    Funds transfer endorsement

    Energy and oilfield services

    Operational technology and vendor access

    Business interruption

    Technology firms

    Client system access

    Cyber paired with tech errors and omissions

    Technology companies are a distinct case. A coding error that harms a client’s business is a professional liability claim, not a cyber claim, so those two policies need to be read together rather than bought separately.

    What Is Changing

    Alberta’s PIPA is under active review. A legislative committee delivered twelve amendment recommendations to the Assembly; government engagement ran through spring 2026, and a reformed bill is expected with Royal Assent anticipated in 2027. The likely direction includes a defined harm threshold, stronger enforcement powers, and mandatory vendor contract terms.

    Two shifts are already reshaping underwriting. Insurers are asking harder questions about supply chain and vendor access, since one compromised software provider can affect hundreds of clients at once. And AI-generated phishing has made fraudulent emails far harder for staff to spot, which is pushing training requirements from optional to expected.

    Businesses that document their privacy practices now will have an easier transition than those starting from scratch after the law changes.


    Frequently Asked Questions

    Is cyber insurance mandatory in Canada? 

    No. But breach notification is legally required under PIPEDA and Alberta’s PIPA, and many client and government contracts require proof of cyber coverage before you can sign.

    How much does cyber insurance cost for a small business in Alberta? 

    Standalone policies commonly run $500 to $3,000 per year. Higher-risk sectors such as healthcare and legal often sit between $3,000 and $7,500.

    Does cyber insurance cover ransomware payments? 

    Usually yes, as a last resort, subject to a sublimit often around 50 percent of the policy limit. Negotiation and forensic costs are typically included.

    Do I report a breach to OIPC Alberta or the federal Privacy Commissioner? 

    Alberta only operations report to the OIPC Alberta under PIPA. Businesses operating across provincial or national borders also report to the federal Office of the Privacy Commissioner under PIPEDA.

    Does my general liability policy cover a data breach? 

    Almost never. Commercial general liability and property policies were written for physical risks and typically exclude or sharply limit cyber losses. Check your policy wording rather than assuming.

    What security controls do insurers require? 

    Multi-factor authentication is effectively mandatory. Most insurers also want tested offline backups, endpoint detection, current patching, and staff phishing training.

    How much coverage does a small business need? 

    Many Alberta small businesses start at $1 million. The right figure depends on how many personal records you hold, since notification costs scale directly with record count.

    Can I add cyber to my existing business policy instead? 

    Yes, and it is cheaper. The tradeoff is much lower limits and narrower wording, which may not cover a full breach response. For most businesses holding customer data, a standalone policy is the better value.

    Getting the Right Policy

    Cyber wording is not standardized the way auto or property forms are. Two policies with identical limits can respond very differently to the same incident, which is the main argument for having a broker compare forms rather than buying whatever appears first online.

    We review your operations, your data, and your existing coverage before recommending anything. If you are weighing this alongside other business coverage, our guides on choosing an insurance broker for your business and small business insurance in Alberta are useful background.

    Ready to see numbers for your business? Request a cyber insurance quote or read more about our cyber liability insurance coverage. We serve businesses in Edmonton, Calgary, and across Alberta and British Columbia.

    Suggested Image Ideas

    1. Hero: Alberta small business owner at a laptop in a real workspace, not a stock hacker in a hoodie. Alt: “Edmonton business owner reviewing cyber insurance coverage options”
    2. Cost table graphic: the premium range table rendered as a branded visual. Alt: “Cyber insurance premium ranges for Alberta businesses by business size”
    3. PIPA reporting flowchart: breach detected, does it meet the RROSH threshold, report to OIPC Alberta or OPC. Alt: “Alberta PIPA breach reporting decision flowchart”
    4. Claims timeline: horizontal graphic of hour 0 to day 90. Alt: “Cyber insurance claim timeline from first call to settlement”
    5. Controls checklist: the five premium-reducing controls as a checklist card. Alt: “Security controls Canadian cyber insurers require for coverage”


  • Insurance in Alberta: What You Need, What It Costs, and What Changes in 2026

    Insurance in Alberta: What You Need, What It Costs, and What Changes in 2026

    Albertans pay more for insurance than almost anyone else in Canada, and the rules are about to change. On January 1, 2027, the province replaces its court-based auto insurance system with a care-based one. Home premiums just posted the steepest provincial increase in the country.

    Choosing the right insurance in Alberta means matching your coverage limits to Alberta-specific risks (hail, wildfire, overland flood, and a liability minimum that has not kept pace with repair costs) rather than buying the cheapest policy that satisfies your lender and the law.

    Key takeaways

    • Alberta’s legal minimum third-party liability is $200,000. Most drivers buy $1 million, and the regulator notes that is now the norm rather than the exception.
    • Care-First auto insurance starts January 1, 2027, with insurer rate increases capped at 5% and individual renewals capped at 10%.
    • Alberta home insurance rose 11.9% year over year in Q2 2026, the largest jump of any province.
    • Average home premiums range from roughly $1,712 in Edmonton to about $3,390 in Fort McMurray.
    • The two most common gaps we see on Alberta policies are a separate hail deductible and a sewer backup sublimit stuck at $10,000.

    What Alberta law actually requires

    Three coverages are mandatory for every registered vehicle. Everything else is either a lender requirement or your choice.

    CoverageRequired byTypical limitWithout it
    Third-party liabilityProvincial law$200,000 minimum; $1M–$2M commonFines, licence suspension, vehicle impoundment
    Accident benefitsProvincial lawSet by regulationSame as above
    Direct Compensation for Property DamageProvincial law since Jan 2022Set by policySame as above
    Collision and comprehensiveYour lender, if financed or leasedDeductible-basedRepairs out of pocket
    Home insuranceYour mortgage lenderRebuild costMortgage default

    The $200,000 floor is the number worth arguing about. A serious injury claim involving lost income and long-term care clears it easily, and anything above the limit comes out of your assets. We recommend $2 million for most households; the premium gap from $1 million is usually small.

    DCPD trips people up more than any other coverage. If another driver is at fault, your own insurer pays for your vehicle damage. If you are at fault, DCPD pays nothing toward your car. That is what collision is for. Our breakdown of what your auto policy actually covers handles the rest, and current requirements are published by the Automobile Insurance Rate Board and the Insurance Bureau of Canada.

    What are insurance costs in Alberta right now

    Auto premiums climbed roughly 57% over ten years, from about $1,153 in early 2015 to $1,817 in late 2024, according to actuarial work commissioned by the province. Home insurance moved further. Statistics Canada measured a 55.8% increase between December 2020 and December 2025, against a national average of 38.6%.

    Here is where things sit by city. Treat these as benchmarks, not quotes.

    CityAverage home premium (annual)Main cost driver
    Edmonton$1,712–$1,883Water damage, sewer backup, winter claims
    Calgary$2,374–$2,500Hail corridor, river flood plains
    Red DeerNear provincial averageHail, wind
    Lethbridge~$2,497Wind, hail, recent sharp increases
    Fort McMurray~$3,390Wildfire exposure

    Alberta absorbed roughly half of Canada’s record $8.6 billion in catastrophic weather claims in 2024. The Calgary hailstorm accounted for about $3 billion of that and the Jasper wildfire about $1.3 billion. Those losses get priced into every policy in the province, even if your own home has never been hit. CBC’s reporting on the Statistics Canada data covers the longer trend.

    Care-First: the January 1, 2027 reset

    Alberta is moving injury claims out of the courts. Instead of suing an at-fault driver, injured drivers will draw expanded benefits from their own insurer.

    Current systemCare-First (from Jan 1, 2027)
    Medical and rehabilitationUp to $50,000 over 2 yearsUnlimited eligible expenses, lifetime
    Income replacementCapped and time-limitedUp to $125,000/year until retirement
    Spousal support on deathLimitedUp to $600,000
    Serious permanent injuryCourt award for pain and sufferingPermanent impairment benefit up to $295,000
    Time to receive benefitsMonths to yearsWeeks
    Right to sue for pain and sufferingYesOnly where the at-fault driver is criminally convicted

    That last row is the trade. You gain speed and much larger benefits. You give up the courtroom in most cases. Whether that is a good deal depends on which side of a collision you end up on.

    An adjusted rate cap arrives alongside it, replacing the Good Driver Rate Cap. Insurers cannot raise rates more than 5% across their whole book, and average drivers see renewals capped at 10%. Recent at-fault collisions or serious convictions can forfeit that protection. The Insurance Bureau of Canada projects average savings near $260 a year, though pricing stays risk-based, so a provincial average tells you little about your own renewal. Details sit on Alberta’s Care-First page.

    What to do between now and your first 2027 renewal:

    1. Note your renewal date. Renew in October 2026 and you sit under the old system for another full year.
    2. Check whether a recent at-fault claim or conviction could cost you cap protection.
    3. Review your liability limit now. Suing gets harder, so your own coverage carries more weight.
    4. Do not cancel optional coverages chasing savings that have not arrived yet.
    5. Have your broker re-shop at renewal instead of accepting the automatic quote. There are 29 companies writing private passenger auto in Alberta.

    Where Alberta home policies quietly leave you exposed

    This is the part aggregator sites cannot tell you, because it only shows up when you read declarations pages for a living.

    A separate hail deductible. Some Alberta policies apply a higher deductible specifically to hail and wind. Your main deductible reads $1,000, your hail deductible reads $5,000, and you find out during a claim. Check the endorsements section.

    Sewer backup capped too low. Plenty of older policies still cap sewer backup at $10,000 or $25,000. Restoring a finished basement in Calgary or Edmonton costs well beyond that. If your basement is developed, push the sublimit to $50,000 or higher.

    Overland flood as an afterthought. Standard policies exclude surface water. Most insurers now sell it as an add-on, though it gets expensive or unavailable near the Bow and Elbow rivers.

    Acreages underwritten differently. Properties outside city limits get assessed on wildfire exposure, distance to a fire hall, and available water for firefighting. A quote built for a city address will not hold.

    Credit consent. Most Alberta carriers price better if you consent to a soft credit check. Decline, and you are usually defaulted into a higher tier. Legal, and rarely explained.

    A real example. A Calgary homeowner came to us happy with her $1,400 policy. Her hail deductible was $5,000, her sewer backup sublimit was $10,000, and her developed basement would cost roughly $60,000 to restore. Restructuring ran $190 more a year and closed a $55,000 hole. Our guide to what home insurance actually covers goes deeper, and these savings tactics recover most of that difference.

    Business owners: the gap nobody mentions

    If you run anything from your house, your home policy almost certainly excludes it. Client visits, stored inventory, and professional liability all fall outside a personal policy. Ransomware exposure has also pushed cyber liability from optional to standard for anyone holding customer data. Shopping commercial coverage? Start with how to choose a broker for your business.

    Life insurance belongs in the same annual review. Mortgage balances and dependents change; coverage rarely gets revisited.

    Broker, agent, or direct

    A broker works independently and quotes several carriers. An agent represents one company. Buying direct means comparing on your own.

    Direct works fine for a simple situation: one newer car, a condo, no claims. It works badly for acreages, home-based businesses, and drivers with a recent claim, because those are the cases where structure matters more than price. Ask any broker how many carriers they place with and what their Alberta Insurance Council licence level is.

    What’s changing next

    Reinsurance costs keep climbing as catastrophic claims mount, which pushes Alberta home rates up regardless of Care-First. Expect steeper discounts for impact-resistant roofing, finer wildfire mapping for foothills and rural properties, and tighter overland flood availability in high-risk zones. Mitigation is turning into a pricing factor rather than a nice gesture.

    FAQ

    Is insurance mandatory in Alberta? Auto insurance is required by law. Home insurance is not, but virtually every mortgage agreement requires it.

    What is the minimum car insurance in Alberta? $200,000 in third-party liability, plus accident benefits and DCPD. Most drivers carry $1 million or more.

    How much is home insurance in Alberta? Roughly $1,800 to $2,400 a year for a detached home, depending on city. Edmonton sits lowest among major centres, Fort McMurray highest.

    Why is Alberta insurance so expensive? Hail, wildfire, and flood losses plus rising rebuild costs. Alberta absorbed about half of Canada’s record catastrophic claims in 2024.

    What is Care-First auto insurance? Alberta’s new system starting January 1, 2027. It replaces most injury lawsuits with expanded benefits from your own insurer, paid in weeks instead of years.

    Will my premium drop in 2027? Projections point to average savings near $260 a year, but pricing stays risk-based. Your result depends on your record, vehicle, and postal code.

    Does home insurance cover hail? Yes, though many Alberta policies apply a separate and higher hail deductible. Check your endorsements.

    Does home insurance cover wildfire? Standard fire coverage applies to wildfire, though insurers may limit exposure in high-risk areas. Confirm rather than assume.

    Do I need overland flood coverage? If you live near a river or in a low-lying area, yes. Standard policies exclude it and sell it as an add-on.

    How often should I review my policies? Yearly, before renewal, and right after any renovation, business start-up, vehicle change, or move.

    Where to start

    Pull your declarations page and check three numbers: your liability limit, your hail deductible, and your sewer backup sublimit. If any of them surprise you, that is your answer.

    We are licensed brokers in Edmonton, Calgary, and British Columbia, placing all lines with multiple carriers. Request a coverage review before your next renewal, or call 780-490-0053 in Edmonton or 403-222-0403 in Calgary. Mid-claim already? Our claims team handles the paperwork and the adjuster calls.

  • Do You Need Life Insurance? A Straight Answer for Alberta Families

    Do You Need Life Insurance? A Straight Answer for Alberta Families

    Most articles on this question are written by companies that only profit when you say yes. We are an independent brokerage in Edmonton and Calgary representing more than 20 A-rated carriers, which means we get paid whether you buy term, permanent, or nothing at all. So this guide includes the part the big insurers leave out: the situations where you genuinely do not need a policy.

    Quick answer: You need life insurance if your death would create financial hardship for someone else. That includes a partner, children, a co-signer on your debt, a business partner, or an estate carrying a mortgage. If nobody depends on your income and your savings already cover your final expenses and debts, you probably do not need coverage right now.

    Key Takeaways

    • Life insurance is not mandatory in Canada, and it is not right for every household.
    • The need peaks in your 30s and 40s, when debt is high and assets are low, then declines as your mortgage shrinks and your children become independent.
    • According to the Canadian Life and Health Insurance Association, roughly 22 million Canadians hold coverage, averaging about $442,000 to $458,000 per household.
    • Workplace group coverage is usually one to two times salary and disappears when you change jobs. Treat it as a starting point, not a plan.
    • Term insurance suits most Alberta families. Permanent policies typically cost five to fifteen times more.
    • Canada Life’s research found only 27% of Canadians knew how much coverage was recommended for their situation.

    What Life Insurance Actually Does

    Life insurance is a contract. You pay a premium, and if you die while the policy is in force, your named beneficiary receives a lump sum called the death benefit. In Canada, that payment is generally tax-free and bypasses probate when a beneficiary is properly designated.

    That is the whole mechanism. It is not an investment, and it is not a savings account. It replaces the money your household would lose if you stopped earning tomorrow.

    You Likely Need Coverage If Any of These Apply

    Children depend on your income

    This is the clearest case. If your income pays for groceries, childcare, and a mortgage, that obligation does not end when you do. Coverage should carry your family until the youngest child is financially independent.

    You share a mortgage that your partner could not carry alone

    A mortgage is most households’ largest single expense, and lenders usually approve it based on two incomes. Life insurance is not required to get a mortgage in Alberta, but a surviving partner facing full payments on half the income is the single most common reason families end up selling a home they wanted to keep.

    Someone co-signed your debt

    If your parents co-signed a student loan or a vehicle, they inherit the payments. A modest policy protects them at a very low cost.

    You support aging parents, a sibling, or a family member with a disability

    Dependency is not always legal. If you send money home monthly or provide care that would otherwise have to be purchased, that support has a replacement cost.

    You are the financial engine of a business

    Banks and the Business Development Bank of Canada routinely require life insurance as collateral on business loans. Partnerships use it to fund buy-sell agreements so a surviving partner can buy out a deceased partner’s family rather than becoming their business partner by accident. If you own an Alberta company, this belongs in the same conversation as your small business insurance coverage.

    You are a stay-at-home parent

    You may not draw a salary, but childcare, transportation, and household management have a market price. Replacing them costs real money.

    You May Not Need Coverage If

    • You are single with no dependents and no co-signed debt.
    • Your savings and assets already cover funeral costs, final taxes, and any outstanding balances.
    • You are retired, your children are independent, your mortgage is paid, and your pension or portfolio supports your spouse without your income.

    If you fall into one of these groups, a broker who insists you need a large permanent policy is selling, not advising. Get a second opinion. That said, revisit the question after any major change, because a new mortgage, a baby, or a business loan flips the answer quickly.

    What Happens in Alberta If You Have No Coverage

    This is where the real cost shows up, and most articles skip it.

    ConsequenceWhat it means in practice
    Debts pass to your estateYour executor settles them before heirs receive anything. Assets may need to be sold.
    CPP death benefit is cappedThe Canada Pension Plan pays a one-time $2,500 benefit. Funerals commonly cost far more.
    Deemed disposition on deathThe Canada Revenue Agency treats capital property as sold at death, which can trigger capital gains tax on a rental property or recreational property.
    Registered accounts collapseAn RRSP or RRIF that does not roll to a spouse is added to your final year of income, often at the top marginal rate.
    Liquidity crunchHeirs may inherit valuable assets and still have no cash to pay the tax bill on them.

    Life insurance is frequently the cheapest way to create cash exactly when the estate needs it most.

    “I Have Coverage Through Work” Is Usually Not Enough

    Group life insurance is a genuine benefit, and if your employer offers it at no cost, take it. Just understand the limits.

    • Typical coverage is one to two times your annual salary, well short of a family’s actual need.
    • It ends when your employment ends, including at layoff or retirement.
    • Portability, where it exists, usually comes with a significant premium increase.
    • Underwriting is loose, which is helpful if your health is poor and irrelevant if it is good.

    Use it as a top-up to a personal policy you control, in the same way you would review your broader household coverage rather than assume one policy handles everything.

    How Much Coverage Do You Actually Need?

    The most reliable framework is DIME, which adds four categories:

    1. Debt. Credit cards, lines of credit, vehicle loans, plus roughly $10,000 to $15,000 for final expenses.
    2. Income. Your annual contribution to the household, multiplied by the number of years your family would need it.
    3. Mortgage. The outstanding balance, not the original amount.
    4. Education. Alberta undergraduate tuition averages just over $8,000 a year, so budget close to $32,000 per child for a four-year degree.

    Worked example. Priya, 38, earns $85,000 in Edmonton. She has a $340,000 mortgage, $18,000 in consumer debt, two children aged 4 and 7, and $60,000 in savings. DIME suggests roughly $340,000 plus $18,000 plus about $500,000 of income replacement over 12 years plus $64,000 in education, less her savings. Her need lands near $860,000.

    Independent analysis by PolicyMe using the same method put the average Albertan’s need just under $400,000, at roughly $44 a month for applicants under 40. Priya’s higher figure reflects two children and a large mortgage, and it illustrates why generic averages make poor planning tools.

    Term or Permanent?

    Match the product to how long the obligation lasts, not to how the product is marketed.

    Term lifePermanent life
    DurationFixed, usually 10 to 30 yearsLifetime, while premiums are paid
    Relative costBaselineRoughly 5 to 15 times higher
    Cash valueNoneBuilds a tax-advantaged value you can borrow against
    RenewalPremiums rise sharply after the termLevel, often paid up after a set period
    Best suited toMortgages, raising children, income replacementEstate taxes, permanent dependants, business succession, charitable legacies

    Most Alberta families with a 20-year window of obligation are best served by term, and by investing the premium difference. Permanent coverage earns its cost when the need never expires, such as a lifelong dependant or a large capital gains liability on a family property.

    Protections Every Alberta Policyholder Should Know

    • Free look period. Canadian policies generally allow at least 10 days to cancel for a full refund.
    • Grace period. Missing a payment does not void coverage immediately. Roughly 30 days is standard.
    • Contestability. Insurers can review claims during the first two years, which is exactly why accurate answers on your application matter more than a favourable rate.
    • Assuris. If a Canadian life insurer fails, Assuris protects death benefits at 100% up to $1,000,000 and 90% above that.
    • Regulation. Every advisor selling life insurance in the province must be licensed through the Alberta Insurance Council. Verify your advisor’s licence before you sign.

    Common Objections, Honestly Answered

    “It is too expensive.” For a healthy non-smoker in their 30s, a substantial term policy often costs less than a monthly phone plan. Price the coverage before you assume.

    “I am young and healthy.” That is precisely when premiums are lowest and approval is easiest. Health changes are not something you can schedule.

    “I will do it when I have kids.” Applying while pregnant or after a new diagnosis narrows your options. Buying early locks the rate.

    “I do not understand the products.” That is a reason to use a broker, not a reason to wait. The same logic applies to choosing an insurance professional for your business.

    Where the Market Is Heading

    Three shifts are worth watching. Accelerated underwriting now approves many healthy applicants without a medical exam, which has cut application times from weeks to days. Living benefits, including critical illness and disability riders, are increasingly bundled into life policies, reflecting that a serious illness is statistically more likely than death during working years. And as mortgage renewals reset at higher rates, more Alberta households are reassessing coverage they set up years ago at much lower debt levels.

    Why an Independent Broker Changes the Outcome

    A single insurer can only quote its own product. We shop more than 20 carriers, which matters most when underwriting is not straightforward, such as a managed health condition, a former smoker, or a physically demanding occupation. Pricing on those files varies widely between insurers.

    We also coordinate life insurance with the rest of your household risk, from home and auto savings opportunities to health coverage gaps, and we stay involved through the claims process when your family needs it most. You can learn more about our team or request a no-obligation quote.

    Frequently Asked Questions

    Is life insurance mandatory in Canada? 

    No. Unlike auto insurance, life insurance is entirely voluntary. Lenders may require it as loan collateral, but no law obliges you to carry it.

    Is the death benefit taxable in Canada? 

    Generally no. A death benefit paid to a named beneficiary is received tax-free. Certain components of permanent policies can have tax consequences, so confirm the details with your advisor.

    Are life insurance premiums tax-deductible? 

    For most individuals, no. The Canada Revenue Agency treats them as a personal expense. Limited exceptions exist, such as policies assigned as collateral for a business loan.

    Do I need life insurance to get a mortgage in Alberta? 

    No. It is not a legal requirement. Lenders will offer their own mortgage protection product, which typically pays the lender rather than your family.

    Is bank mortgage insurance the same as life insurance? 

    No. Bank coverage usually declines as your balance drops, pays your lender directly, and cannot be moved to a new lender. A personal term policy pays your beneficiary, who can choose how to use it.

    Do I need life insurance if I am single with no children? 

    Often not. Consider it if you have co-signed debt, support a family member financially, or want to lock in a low rate before your health or family situation changes.

    Do I still need coverage in retirement? 

    Frequently not, if your mortgage is paid and your spouse is secure without your income. It can still make sense for estate taxes on a rental or recreational property, or for a lifelong dependant.

    Can I get coverage with a pre-existing condition? 

    Usually yes. Pricing varies significantly between insurers, which is where multi-carrier shopping matters most. No medical options exist at higher premiums.

    The Bottom Line

    The honest answer is that life insurance solves one specific problem: someone loses money when you die. If that describes your household, coverage is one of the most efficient purchases available to you, and it is the cheapest today. If it does not describe your household, keep your money and revisit the question when your circumstances change.

    Either way, the decision should follow a real analysis of your debts, dependents, and timelines rather than a sales pitch. If you want that analysis for your own numbers, our licensed advisors in Edmonton, Calgary, and British Columbia are happy to walk through it with you at no cost. Call 780-490-0053 or get in touch.

  • Cyber Liability Insurance for Alberta Businesses

    Cyber Liability Insurance for Alberta Businesses

    A single phishing email can cost an Alberta business more than a year of revenue. And unlike a fire or a break-in, your commercial property policy almost certainly will not respond.

    That gap is what cyber liability insurance exists to close.

    Key Takeaways

    • Cyber liability insurance covers the financial fallout of data breaches, ransomware, and network failures, including recovery costs, legal defence, and mandatory breach notification.
    • Most Alberta small businesses pay roughly $500 to $3,000 per year for a standalone policy, depending on revenue, industry, and security controls.
    • Standard Commercial General Liability policies exclude cyber risk. If you have not bought it separately, you are self-insuring.
    • Under Alberta’s PIPA, reporting a serious breach to the Privacy Commissioner is mandatory, not optional.
    • Insurers now underwrite based on your actual security practices. Multi-factor authentication and tested backups often decide whether you get a quote at all.

    What Is Cyber Liability Insurance?

    Cyber liability insurance is business insurance that pays for the costs and legal claims that follow a cyber incident, such as a data breach, ransomware attack, or system intrusion. It typically covers forensic investigation, data restoration, lost income during downtime, customer notification, credit monitoring, legal defence, and regulatory response.

    You will see it sold under several names. Cyber insurance, cyber risk insurance, data breach insurance, and cybersecurity insurance all describe broadly the same product. The differences lie in the policy wording, not the label.

    Does Your Alberta Business Actually Need It?

    Skip the guesswork. If any of the following is true, you have a real exposure:

    • You store customer names, emails, addresses, or payment details
    • You process card payments or run a point-of-sale system
    • You send or receive invoices by email
    • You use cloud software such as Microsoft 365, QuickBooks, or Google Workspace
    • Staff work remotely or use personal devices
    • You hold employee records containing SINs or banking information
    • You handle health information as a clinic, pharmacy, or dental practice

    That covers nearly every operating business in Edmonton and Calgary, including trades, retailers, consultants, and non-profits.

    The scale of the risk is not theoretical. IBM’s 2025 Cost of a Data Breach research placed the average Canadian breach at roughly CA$6.98 million, up more than 10 percent year over year, with phishing-initiated breaches costing even more. Small businesses rarely see numbers that large, but they also rarely have the cash reserves to absorb a $75,000 incident.

    What Cyber Liability Insurance Covers

    Coverage splits into two halves. Most businesses need both.

    First-Party CoverageThird-Party Coverage
    Protects againstLosses to your own businessClaims made against you by others
    Typically includesForensic investigation, data restoration, business interruption, cyber extortion and ransomware costs, breach notification, credit monitoring, crisis PRLegal defence, settlements, court-ordered damages, regulatory proceedings, privacy liability
    Example triggerRansomware locks your server for six daysA client sues after their data is exposed on your system
    Who needs it mostAnyone storing customer or employee dataFirms that host, manage, or process client data

    If you provide IT services, bookkeeping, or software to clients, third-party coverage matters more than most owners realise. A mistake on a client’s network can become your liability. This overlaps with professional liability, so it is worth reviewing both alongside your broader business insurance coverage.

    What It Does Not Cover

    This is where claims get denied, and where most competitor pages stay silent. Ask your broker about all six:

    1. Social engineering and funds transfer fraud. Often a sub-limit, not full coverage. A $2 million policy may cap wire fraud at $100,000.
    2. Prior known incidents. Were you aware of it before the policy started?
    3. Unpatched or unsupported systems. Some wording excludes losses traced to known vulnerabilities you failed to fix.
    4. Betterment. The policy restores what you had. It will not fund a system upgrade.
    5. War and state-sponsored attacks. Increasingly excluded across the market.
    6. Application misrepresentation. If you said you had multi-factor authentication everywhere and you did not, the claim can be voided.

    That last point causes more denied claims than any technical exclusion. Answer the application honestly, even when the honest answer is uncomfortable.

    How Much Does Cyber Liability Insurance Cost in Alberta?

    Pricing varies widely, but the market has settled into recognisable bands.

    Business ProfileCoverage LimitTypical Annual Premium
    Cyber endorsement added to existing policy$50,000 to $250,000$100 to $250
    Micro business, 1 to 10 staff$250,000 to $500,000$500 to $1,500
    Small business under $5M revenue$1 million$1,200 to $4,000
    Professional services firm, ~50 staff$5M to $10M$4,000 to $12,000

    Figures reflect published Canadian broker and market data as of 2026. Your quote will differ. Retentions on larger policies often start near $10,000.

    Seven factors drive your number:

    1. Annual revenue
    2. Industry and data sensitivity
    3. Volume of records stored
    4. Security controls in place
    5. Claims history
    6. Coverage limit selected
    7. Deductible or retention chosen

    Security posture is now the strongest lever. Two identical firms in the same sector can receive very different pricing based purely on control maturity.

    What Insurers Require Before They Will Quote You

    Underwriting has tightened considerably since 2021. Most Canadian carriers now expect:

    • Multi-factor authentication on email, VPN, and all administrator accounts
    • Endpoint detection and response software, not just basic antivirus
    • Backups that are tested and stored offline or in immutable storage
    • A documented patching schedule
    • Employee phishing awareness training
    • A written incident response plan

    Businesses that can evidence all six typically get better terms. Those who cannot may find fewer carriers willing to compete for the risk.

    Your Legal Obligations After a Breach in Alberta

    Alberta is stricter than most provinces, and this is where insurance quietly earns its premium.

    Alberta PIPA. Private-sector organisations must report a breach to the Office of the Information and Privacy Commissioner of Alberta without unreasonable delay when there is a “real risk of significant harm” to an individual, and notify affected individuals directly. The OIPC breach notification requirements set out the process and forms.

    PIPEDA. If your business operates across provincial or international borders, federal reporting to the Office of the Privacy Commissioner of Canada applies as well. Breach reporting has been mandatory since November 2018, and you must keep records of every breach for two years. Full guidance is available from the Privacy Commissioner of Canada.

    Health Information Act. Clinics, dentists, and pharmacies acting as custodians face additional notification duties as soon as practicable.

    The Government of Alberta publishes a plain-language summary of organisational responsibilities under PIPA, and the Canadian Centre for Cyber Security offers free baseline controls guidance for small and medium organisations.

    Notification is expensive. Legal review, mailing, call centre capacity, and credit monitoring add up fast, and a cyber policy is what pays for it.

    A Real-World Scenario

    A Calgary construction firm receives an emailed invoice that appears to come from a long-standing supplier. The banking details have been changed. Accounts payable wires $84,000.

    The supplier’s email account had been compromised weeks earlier. Nobody at the construction firm did anything obviously wrong.

    Without cyber coverage, that is $84,000 gone. With a policy that includes social engineering fraud, most of it is recoverable, subject to the sub-limit and deductible. This is precisely why reading the sub-limits matters more than reading the headline limit.

    Common Challenges and Practical Solutions

    ChallengePractical Solution
    “My IT provider handles security, so I’m covered.”Security reduces risk. It does not transfer financial liability. You still need the policy.
    “My business is too small to be targeted.”Attackers automate. Smaller firms are targeted precisely because defences are thinner.
    Confusing quotes with different sub-limitsAsk brokers to compare on identical limits, retentions, and coverage triggers.
    Failing the MFA question on the applicationDeploy MFA before applying. It improves both eligibility and price.
    Not knowing who to call at 2 a.m.Confirm your policy includes a 24/7 breach hotline, then post the number where staff can find it.

    Where Cyber Coverage Is Heading

    Three shifts are worth watching:

    • Alberta PIPA reform. A modernised bill is anticipated in the current legislative cycle, with stronger accountability provisions and rules addressing automated decision-making.
    • AI-related exclusions. Carriers are beginning to clarify how policies respond to incidents involving AI tools and AI-assisted attacks.
    • Security-linked pricing. Expect continuous verification of controls rather than a once-a-year questionnaire.

    Frequently Asked Questions

    How much does cyber liability insurance cost in Alberta? 

    Most small businesses pay between $500 and $3,000 per year for a standalone policy. A basic endorsement on an existing commercial policy can start near $100 to $250, but with much lower limits.

    Does my commercial general liability policy cover a data breach? 

    Almost never. CGL policies were built for bodily injury and physical property damage. Cyber risk is typically excluded outright.

    Is cyber insurance mandatory in Canada? 

    No. But breach reporting is. Alberta PIPA and PIPEDA both impose legal notification duties, and those costs land on you whether or not you are insured.

    What is the difference between cyber insurance and cyber liability insurance? 

    The terms are used interchangeably in the Canadian market. Compare the actual coverage grid rather than the product name.

    Does cyber insurance cover ransom payments? 

    Many policies include cyber extortion coverage, subject to sub-limits, insurer approval, and applicable sanctions law. Confirm this specifically.

    Do I need multi-factor authentication to get covered? 

    For most carriers, yes. MFA on email, VPN, and admin accounts is now close to a minimum entry requirement.

    How quickly can coverage be arranged? 

    For a straightforward small business, often within one to two business days once the application is complete. You can request a quote online to start.

    The Bottom Line

    Cyber liability insurance is no longer a specialty product for tech firms. If your business runs on email, stores customer information, or accepts digital payments, the exposure is already there.

    The right policy does two things. It absorbs the financial hit, and it puts a specialist response team on your side within hours rather than weeks.

    Start by reviewing what your current small business insurance actually includes, then close the gaps. Our team explains why every business needs cyber insurance in more detail, and if you are still comparing providers, this guide on choosing the right insurance broker for your business is a useful starting point.

    Alliance Insurance is a licensed brokerage serving Edmonton, Calgary, and communities across Alberta and British Columbia. We work with multiple Canadian carriers to structure cyber coverage around how your business actually operates, and we stay involved through the claims process if something goes wrong.

    Call 780-490-0053 (Edmonton) or 403-222-0403 (Calgary), or request a free quote today.