

Renting a home, apartment, or condo in Ontario comes with an important insurance distinction: your landlord’s policy protects the building and the landlord’s financial interests, not everything inside your unit and not every risk you may face as a tenant.
That is why tenant insurance in Ontario matters. It is designed to protect your belongings, your personal liability, and your living arrangements if an insured loss makes your rental temporarily uninhabitable.
If you are searching for Tenant Insurance ON, tenant insurance Ontario, or affordable home insurance Ontario options for a rental, understanding this difference can help you choose coverage with greater confidence.
Your Landlord’s Policy Protects the Building
A landlord’s insurance policy typically protects the physical property, including the structure, plumbing, heating systems, permanent fixtures, and property belonging to the landlord.
It may also include the landlord’s liability coverage and protection for lost rental income after certain insured losses.
However, the landlord’s policy generally does not protect:
- Your clothing, furniture, electronics, or personal belongings
- Your personal liability if you accidentally cause damage
- Your additional living expenses if you must leave the unit after an insured loss
- Your valuables beyond the coverage available under your own policy
- Your belongings while temporarily away from home, subject to policy terms
The distinction is straightforward: the landlord insures the rental property. You insure your life inside it.
The Insurance Bureau of Canada explains that tenant insurance commonly combines personal property, personal liability, and additional living expense coverage. You can review its overview of tenant and renter’s insurance coverage for additional background.
Protect What You Own. Cover Your Liability.
A tenant insurance policy is designed around the risks that follow you as a renter.
Personal contents coverage
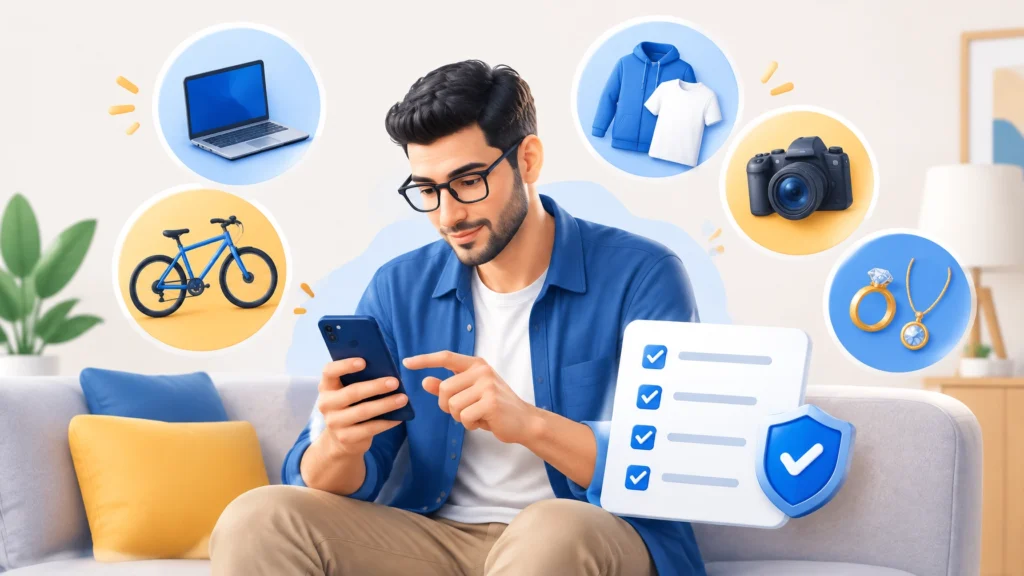
Contents coverage helps protect your belongings against covered losses such as fire, theft, vandalism, and certain types of sudden water damage. Depending on your policy, coverage may apply both inside your rental and while your belongings are temporarily away from home.
Your contents may include:
- Clothing and shoes
- Furniture and household items
- Computers, tablets, and televisions
- Kitchen appliances and personal electronics
- Sporting equipment and bicycles
- Books, tools, and personal collections
The right contents limit is not simply the amount you think your belongings are worth today. It should reflect what you would need to replace the essentials and rebuild your day-to-day life after a serious loss.
Personal liability coverage
Personal liability coverage may protect you if you are legally responsible for unintentionally injuring someone or damaging someone else’s property.
For a tenant, that could include accidental damage to:
- Your rented unit
- The landlord’s building
- A neighbouring apartment or condo unit
- Common areas of a building
- Another person’s property
Coverage is subject to your policy wording, exclusions, limits, and deductible. It may also provide legal defence costs when a covered claim is brought against you.
Additional living expenses
If an insured loss makes your rental temporarily uninhabitable, additional living expense coverage, sometimes called loss of use coverage, may help pay for necessary extra costs.
Depending on the policy, this can include temporary accommodation, increased meal costs, storage, and other reasonable expenses while your home is being repaired.
This coverage is not intended to improve your lifestyle or pay every expense you normally have. It is designed to help you maintain reasonable living arrangements after a covered event.
One Incident Can Affect Two Neighbouring Units
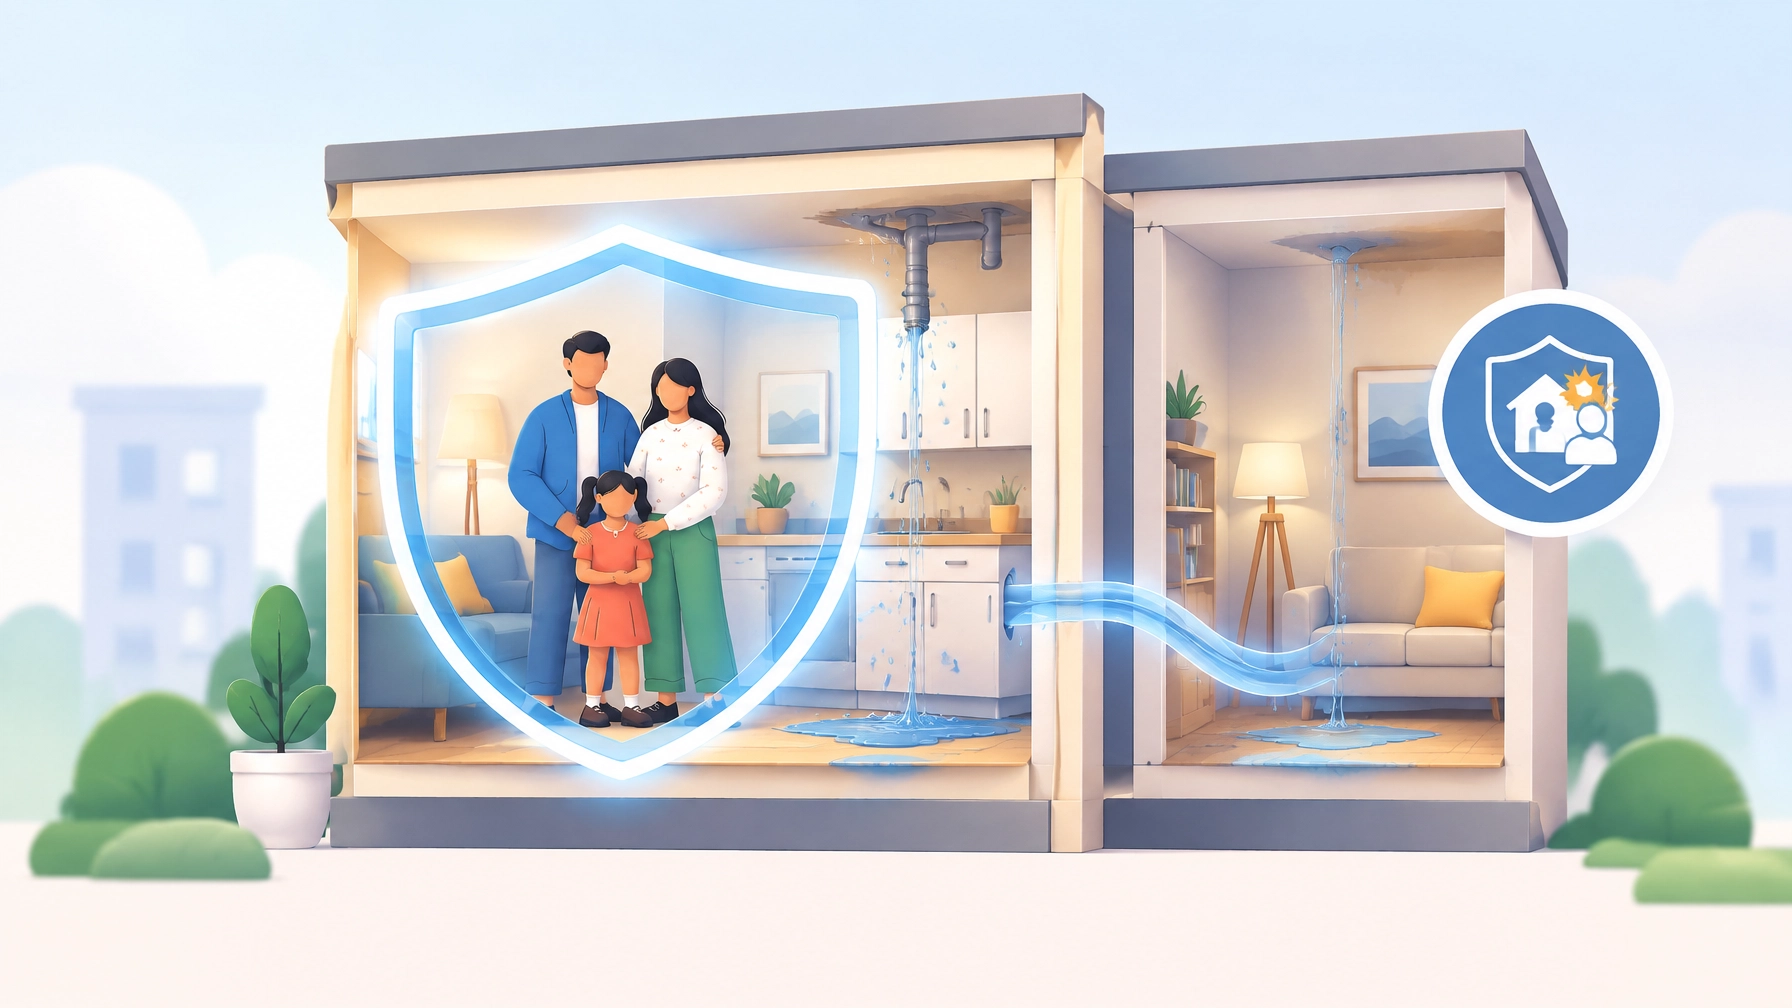
Consider a water escape from a washing machine, dishwasher, sink, or toilet. The water may damage your flooring and belongings, then move through walls or ceilings into the unit below.
A kitchen fire can create a similar problem. Even if the fire starts in your unit, smoke, water, and fire damage may affect neighbouring homes and shared building areas.
Your landlord’s policy may respond to damage to the building. But if you are found legally responsible for causing the loss, your own personal liability coverage may become important.
This is one reason a landlord or condo owner may require proof of tenant insurance. Liability coverage helps provide a layer of protection for everyone involved, including you, the property owner, and neighbouring residents.
Consider Optional Endorsements Carefully
A standard tenant policy may not automatically cover every risk that matters to you. Depending on the insurer and your rental property, optional endorsements may be available for:
Sewer backup
Sewer backup coverage can help protect against damage caused by water backing up through drains or sewer lines. This is different from every other type of water loss, so ask how your policy treats it.
Scheduled valuables
Jewellery, watches, artwork, collectibles, cameras, and other high-value items may have special limits under a standard policy. Scheduling an item individually may provide broader or higher coverage, often subject to an appraisal or proof of value.
Bicycle and theft-away-from-home coverage
Your bicycle or sports equipment may have a sub-limit, deductible, or special conditions. Personal property away from home may be covered, but the extent of coverage depends on the policy.
If you own items that would be difficult or expensive to replace, discuss them with an Alliance consultant rather than assuming a basic contents limit will be enough.
Know What Tenant Insurance Does Not Cover
Tenant insurance is valuable, but it is not a maintenance contract or a guarantee against every type of loss.
Common exclusions or limitations may include:
- Intentional acts: Damage deliberately caused by an insured person is generally excluded.
- Normal wear and tear: Insurance is designed for sudden and accidental losses, not gradual deterioration or maintenance.
- Pests and infestation: Damage caused by insects, rodents, or other pests is commonly excluded.
- Business inventory and equipment: Property used for a home-based business may have limited coverage or may require commercial insurance.
- High-value property above policy sub-limits: Jewellery, bicycles, electronics, cash, and collectibles may have specific limits.
- Uninsured water losses: Sewer backup, overland water, or other water-related events may require separate endorsements.
If you operate a business from your rental, store inventory at home, or regularly meet clients there, tell your insurance representative. A standard tenant policy may not be designed for those exposures. You may need a home-business endorsement or separate commercial insurance.
How Much Does Tenant Insurance Cost in Ontario?
The cost of tenant insurance in Ontario varies from one renter to another. Premiums are influenced by factors such as:
- Your contents coverage limit
- The liability limit you select
- Your deductible
- The rental property’s location and construction
- The building’s age and claims history
- Your personal insurance and claims history
- Optional endorsements
- Safety and security features at the property
A lower premium is not always the better choice if it leaves you without enough contents coverage or the liability limit required by your lease.
You can often adjust the deductible and coverage limits to suit your budget, but those decisions should be made deliberately. The goal is a practical, tailored policy, not simply the cheapest policy available.
Review Your Lease and Condo Requirements
Tenant insurance is not automatically required by Ontario law in every rental. However, many landlords include an insurance requirement in the lease.
If your rental agreement requires liability coverage, you are generally expected to maintain that coverage. Ontario’s Steps to Justice guidance explains that a lease may require tenant insurance with liability coverage, while contents insurance cannot be required in the same way.
Rental condos can involve additional requirements. The condo corporation may have rules or bylaws that affect occupants, while the unit owner may include insurance requirements in your lease.
When your landlord or property manager asks for proof of insurance, the certificate or policy confirmation should clearly show:
- Your name as the insured tenant
- The rental property address
- The policy’s effective date and expiry date
- The personal liability limit
- The insurer or brokerage information
- The policy number, where applicable
If you move, renew your lease, or change insurers, provide updated proof when requested.
Build a Practical Tenant Insurance Checklist
Before purchasing or renewing tenant insurance in Ontario, take these steps:
- Create a home inventory. Photograph important belongings and keep receipts, appraisals, or purchase records where possible.
- Choose a realistic contents limit. Consider what it would cost to replace your clothing, furniture, electronics, and household essentials.
- Select your deductible deliberately. A higher deductible may reduce the premium, but you should be comfortable paying it after a claim.
- Confirm your liability requirement. Check your lease for the minimum limit requested by your landlord or property manager.
- Ask about endorsements. Review sewer backup, scheduled valuables, bicycles, and property away from home.
- Disclose home business activity. Inventory, equipment, or customer visits may need additional protection.
- Review annually. Your belongings, address, household members, and insurance needs can change over time.
Choose Guidance Built Around Your Rental
Tenant insurance in Ontario should be clear, practical, and tailored to your circumstances. It should protect what matters to you without adding coverage you do not need or leaving important gaps unexplained.
At Alliance Insurance Associates, our consultants help Ontario renters compare coverage, understand liability protection, review policy limits, and identify practical options for their belongings and living arrangements. We focus on risk management and informed decisions, not generic insurance templates.
Book a tenant insurance review with Alliance Insurance Associates to discuss your rental, contents, liability requirements, and available coverage options.
Frequently Asked Questions
Does my landlord’s insurance cover my belongings?
Usually, no. The landlord’s policy generally protects the building, the landlord’s property, and the landlord’s liability. Your personal belongings require your own tenant insurance policy.
Does tenant insurance cover accidental damage to my rental?
Personal liability coverage may respond when you are legally responsible for accidental damage to the unit or other property. Coverage depends on the policy wording, exclusions, and limits.
Is tenant insurance mandatory in Ontario?
Ontario law does not require every renter to carry tenant insurance. However, a landlord may include a liability insurance requirement in the lease.
Does tenant insurance cover a hotel if my rental becomes uninhabitable?
Additional living expense coverage may help with necessary extra costs after a covered loss makes your rental uninhabitable. Limits and conditions apply.
Can tenant insurance cover my business inventory?
Business property and inventory may have limited coverage under a personal tenant policy. If you operate a business from home, discuss your activities with an insurance consultant before assuming you are fully protected.