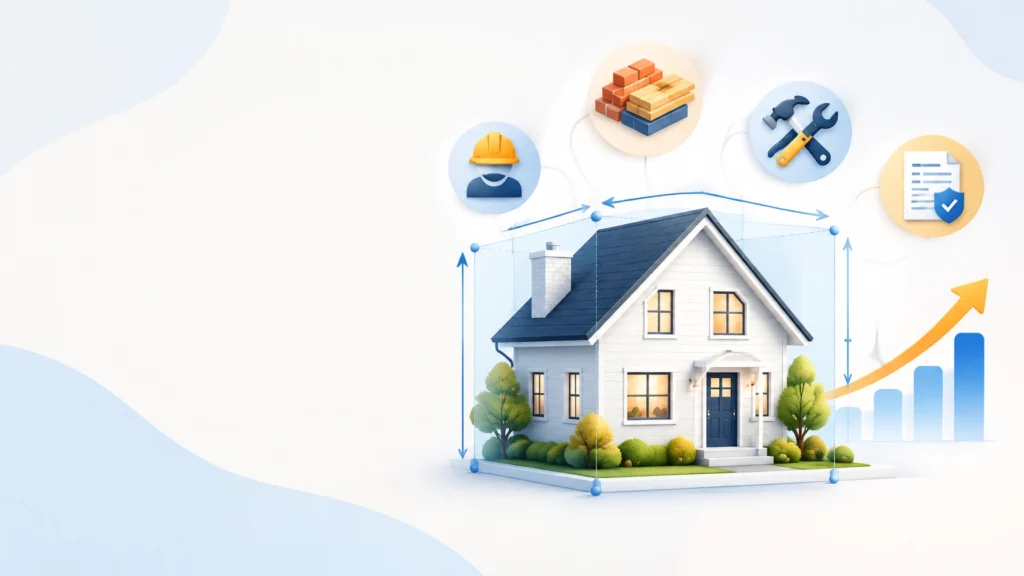



Your home insurance limit may have been updated over the years, but that does not necessarily mean it reflects the true cost of rebuilding your home today.
Construction materials, skilled labour, permits, demolition, debris removal, and building-code requirements can all affect the cost of restoring a property after a major loss. If your dwelling limit was set several years ago and only adjusted by a standard inflation factor, there may be a gap between your coverage and the actual rebuild cost.
That does not mean you need to worry. It does mean your home owners insurance deserves a careful review, especially at renewal or after a renovation.
At Alliance Insurance Associates, we help homeowners look beyond a policy’s headline limit. Our role is to understand your property, identify potential gaps, and help you choose practical protection for what matters most.
Market Value and Rebuild Cost Are Different
The market value of your home is what a buyer may be willing to pay for the property. It can include:
- The location and neighbourhood
- The land beneath the home
- Nearby schools and amenities
- Local demand
- The age and condition of the property
- Real estate market conditions
The rebuild cost is different. It is the estimated cost to reconstruct the home after a covered total loss using comparable materials and current labour rates.
For insurance purposes, the land is not rebuilt. Location-based market value is not rebuilt either. Your home insurance dwelling limit is intended to reflect the structure itself, including items such as the foundation, framing, roof, wiring, plumbing, heating systems, attached garage, and built-in features.
The Insurance Bureau of Canada explains that a home’s replacement value may differ from its market value and municipal tax assessment. The Financial Consumer Agency of Canada also notes that a coverage limit is the maximum an insurer will pay under the policy.

Check What Your Dwelling Limit Is Designed to Cover
Your policy’s dwelling limit, sometimes called building coverage, generally applies to the primary structure of your home. It may also consider attached garages and certain built-in fixtures.
The limit should be based on current replacement or rebuild cost, not simply:
- Your purchase price
- Your mortgage balance
- Your municipal tax assessment
- The amount you paid for the property years ago
- A basic inflation adjustment
A rebuild-cost estimate may consider the home’s size, age, construction type, number of storeys, roofing, heating, fireplaces, custom features, and the location of the nearest fire department or hydrant.
Your policy may also provide separate limits for detached structures, personal belongings, additional living expenses, and liability. These amounts should be reviewed alongside the dwelling limit so your coverage works as a complete plan.
Understand Replacement Cost and Actual Cash Value
The way a claim is settled can significantly affect the amount you receive.
Replacement cost
Replacement cost coverage is intended to pay the cost of repairing or replacing damaged property with new materials of similar kind and quality, subject to the policy limit and conditions.
For a home, this may help fund reconstruction without deducting depreciation from every building component. However, you generally still need to meet the policy’s requirements, use approved settlement methods, and maintain sufficient insurance.
For contents, replacement cost may help replace an older appliance, computer, or piece of furniture with a comparable new item rather than paying only what the older item was worth immediately before the loss.
Actual cash value
Actual cash value generally reflects replacement cost minus depreciation. Depreciation considers the age, condition, and expected useful life of the property.
For example, an older roof may have a much lower actual cash value than the cost of installing a new roof. If your policy applies actual cash value to that item, the claim payment may not be enough to fund a complete replacement.
The Financial Consumer Agency of Canada provides a helpful explanation of the difference between actual cash value and replacement value. When reviewing home insurance in Ontario, Alberta, or BC, ask which settlement basis applies to the building, contents, roof, and other important property features.
Consider Guaranteed or Extended Replacement Cost
Some policies offer additional protection above the stated dwelling limit. The terminology and conditions vary by insurer, so the policy wording matters.
Guaranteed replacement cost
Guaranteed replacement cost may provide protection if the actual cost to rebuild exceeds the dwelling limit after a covered loss. This coverage is often subject to conditions, such as:
- The home must be insured to the insurer’s full replacement-cost estimate
- Property information must be accurate and current
- Renovations and improvements must be reported
- The home must meet applicable policy requirements
- The insurer may need to approve the rebuilding plan or contractor
Guaranteed replacement cost is not a reason to ignore your policy limit. Keeping the limit accurate remains important.
Extended replacement cost
Extended replacement cost may provide a defined percentage above the dwelling limit to address unexpected cost increases. This can be helpful when a widespread event increases demand for contractors, materials, and temporary housing.
Availability, percentages, exclusions, and conditions differ between insurance companies. A coverage review can help you understand whether this option is available and appropriate for your home.
Look for Common Coverage Gaps
A home may be insured at an appropriate level when the policy is first written, then become less accurately described over time. Certain changes deserve particular attention.
Renovations and additions
A finished basement, new bathroom, expanded kitchen, addition, or converted garage can change the cost to rebuild. Even high-quality flooring, cabinetry, windows, insulation, and electrical work may affect the replacement estimate.
Tell your insurance representative about completed and planned renovations before work begins whenever possible.
Custom features and specialty materials
Custom millwork, stonework, heritage details, imported finishes, solar equipment, smart-home systems, and specialty heating systems may cost more to replace than standard materials.
The more distinctive your home is, the more important accurate information becomes.
Building-code upgrades
After a major loss, rebuilding may require your home to meet current building codes and municipal requirements. This can involve upgrades to:
- Electrical systems
- Plumbing
- Insulation and energy efficiency
- Fire separation
- Smoke and fire protection
- Structural components
- Accessibility or safety features
Some policies include by-law or building-code coverage. Others may provide only a limited amount unless an endorsement is added. Ask how your policy responds to these additional costs.
Detached structures
Detached garages, workshops, sheds, pools, fences, gazebos, and other structures may be insured under separate limits or percentages. A new workshop or large detached garage may exceed the amount automatically provided by the policy.
Review these structures individually if they represent a significant investment.

Review Your Coverage at Renewal
A practical renewal review does not need to be complicated. Start with your declarations page and ask:
- What is my current dwelling limit?
- When was the rebuild-cost estimate last reviewed?
- Have I completed renovations or additions?
- Are custom features and specialty materials included?
- How are detached structures covered?
- Do I have replacement cost or actual cash value coverage?
- Is guaranteed or extended replacement cost available?
- What limit applies to building-code or by-law upgrades?
- Are my contents insured for replacement cost?
- Are additional living expenses sufficient for current rental and accommodation costs?
Keep photos, invoices, renovation records, appraisals, and a home inventory in a secure location. These records can help your insurance professional understand the property and may be useful in the event of a claim.
What Renters and Condo Owners Should Review
Not every residence needs a homeowner’s dwelling limit.
Renters
If you rent a home or apartment, the landlord generally insures the building. Your tenant or renters insurance should focus on:
- Personal belongings
- Personal liability
- Additional living expenses
- Improvements or upgrades you are responsible for
- Any business equipment or home-based business activity
The FCAC’s home insurance guidance explains that renters should consider enough coverage to replace their possessions.
Condo owners
Condo or strata corporation insurance generally covers the building and common areas, but your unit-owner policy may need to cover:
- Personal belongings
- Improvements and betterments
- Personal liability
- Additional living expenses
- Contingency coverage
- Loss assessment coverage
In BC, condo properties are commonly referred to as strata properties. The IBC overview of condo and strata coverage explains why the corporation’s policy and your unit-owner policy work together.
Get a Clear, Practical Coverage Review
Home insurance should not be based on a generic number or an outdated estimate. Your property, renovation history, location, construction type, and priorities all matter.
Alliance Insurance Associates provides tailored home and property insurance guidance in Ontario and Alberta. In BC, we operate as Alliance Associates, offering home, property, and commercial/business insurance solutions.
Our consultants help you compare coverage, understand settlement options, review rebuild-cost details, and identify practical gaps without adding unnecessary complexity.

If you are reviewing home owners insurance, property insurance in Ontario, or home insurance in Ontario, now is a good time to check whether your policy still reflects the home you own today. Homeowners in Alberta and BC can benefit from the same review: particularly after renovations, property upgrades, or changes in local construction costs.
Book a coverage review with an Alliance consultant or learn more about our home insurance services. We are here to help you make an informed decision and feel confident that your coverage is designed around what matters most.
This article provides general information and does not replace your insurance policy wording or advice from a licensed insurance professional. Coverage, exclusions, limits, and eligibility vary by insurer and province.